Executive Overview
In a strategic move ahead of the peak holiday shopping season, Apple has rolled out one of the most lucrative promotional offers in the history of its financial services portfolio. New applicants for the Apple Card who successfully register and are approved by December 10 will be eligible to earn double their standard Daily Cash rewards across the board for an entire year.
For consumers deeply embedded in the Apple ecosystem, this translates to an unprecedented cash-back earning potential of up to 6% on purchases, alongside a ceiling of $1,000 in promotional bonus cash. The campaign, which marks a significant departure from Apple’s traditionally conservative promotional strategy for the credit card, is designed to capture market share during the most lucrative retail window of the year.
By scaling rewards up to double digits for everyday transactions, Apple—in partnership with issuing bank Goldman Sachs—is not only targeting holiday shoppers looking to maximize credit card rewards, but is also positioning the Apple Card as a premier financial tool for long-term daily use. This comprehensive report breaks down the mechanics of the promotion, evaluates its financial impact for consumers, and analyzes what this aggressive push signifies for Apple’s broader fintech ambitions.
Detailed Chronology of the Promotion
The rollout of the "Double Daily Cash" promotion began making waves across tech and financial sectors in mid-November, catching consumers and industry analysts by surprise with its unusually high reward ceilings.
The Leak and Official Debut
The promotion first surfaced via industry tracking and consumer reports before being formally detailed by publications such as MacRumors. Unlike standard welcome offers that typically rely on a one-time lump-sum bonus (e.g., spend $1,000 in the first three months to receive a $200 statement credit), Apple’s new campaign fundamentally alters the underlying reward structure of the card for an extended 365-day period.
To qualify for this lucrative first-year bonus, applicants must bypass the standard application channels found on general web searches and instead apply directly through a dedicated, exclusive promotional landing page provided by Apple.

Key Milestones and Deadlines
- Mid-November: Initial discovery and confirmation of the limited-time promotion across financial news outlets.
- December 10: The hard application deadline. Prospective cardholders must apply and be approved by midnight on this date to lock in the 12-month double-reward tier.
- First 365 Days: The promotion period begins immediately upon account opening and runs continuously for one full year, subject to the $1,000 bonus cap.
Financial Breakdown: How the Numbers Work
To fully appreciate the scope of this promotion, it is necessary to examine how Apple’s signature "Daily Cash" program traditionally operates and how it transforms under the current holiday incentive.
Understanding Standard Daily Cash
Apple famously markets its credit card around a "no points, no gimmicks" philosophy. Instead of forcing users to accumulate opaque points that must be calculated, converted, or redeemed through restrictive travel portals, Daily Cash is paid out as direct, real-world cash deposited straight into the user’s Apple Cash card on a daily basis.
Under normal operating conditions, the baseline reward tiers are structured as follows:
- 3% Cash Back: Earned on all purchases made directly with Apple (including hardware, software, subscriptions, and services), as well as select merchant partners such as Uber, Uber Eats, Walgreens, ExxonMobil, and Nike, provided the transaction is completed using Apple Pay.
- 2% Cash Back: Earned on any purchase made using Apple Pay, regardless of the merchant.
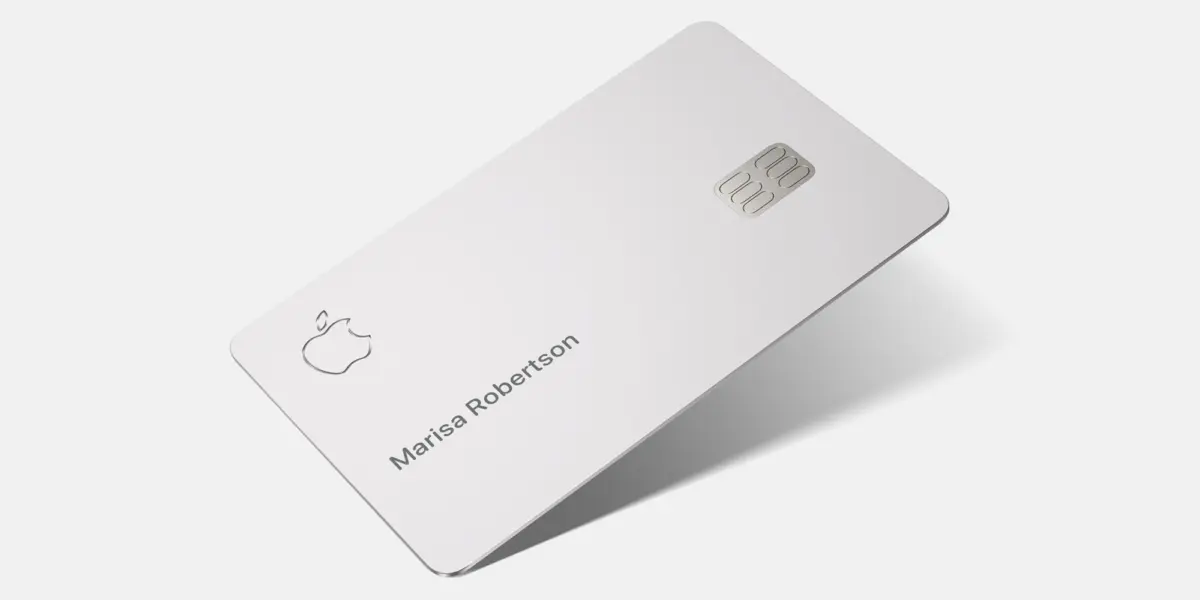
- 1% Cash Back: Earned on purchases where Apple Pay is not accepted and the user must resort to using the physical titanium Apple Card.
The Promos Transformative Rates
When applying through the exclusive promotional link prior to the December 10 cutoff, these figures are effectively doubled for the first year of card ownership:
- 6% Cash Back (Up from 3%): Applicable to all purchases from Apple and select participating merchant partners when checked out via Apple Pay.
- 4% Cash Back (Up from 2%): Applicable to all everyday purchases completed using Apple Pay globally.
- 2% Cash Back (Up from 1%): Applicable to fallback transactions executed using the physical titanium card or virtual card number when Apple Pay is unavailable.
The $1,000 Bonus Cap Explained
While the prospect of earning up to 6% back is undeniably attractive, savvy consumers must take note of the fine print. Apple has instituted a strict $1,000 limit on the additional Bonus Daily Cash that can be earned through this specific promotion.
To put this into perspective, let’s look at the math for the 4% Apple Pay tier:
- A standard user earning 2% would need to spend $50,000 to earn $1,000 in cash back.
- Under the promotional 4% tier, the extra 2% bonus accumulates until it hits the $1,000 ceiling.
- This means a cardholder would need to charge approximately $50,000 in eligible promotional spend within their first year to max out the $1,000 bonus pool.
Once that $1,000 bonus threshold is crossed, the account automatically reverts to standard rates (1%, 2%, and 3%) for the remainder of the 12-month window. For the vast majority of everyday consumers, this cap is more than generous enough to cover heavy holiday spending, travel, and routine grocery purchases without ever hitting the ceiling.
Supporting Context & Strategic Metrics
Apple’s decision to supercharge its credit card rewards program does not happen in a vacuum. It reflects a calculated effort to deepen consumer engagement with Apple Pay, drive hardware sales during a critical economic cycle, and compete more aggressively in the crowded digital wallet and credit card arena.
The Rise of Apple Financial Services
Since the Apple Card’s debut in 2019, Apple has steadily expanded its footprint in consumer finance. Beyond the credit card itself, the tech giant introduced Apple Pay Later (though later restructured) and the high-yield Apple Savings account in partnership with Goldman Sachs.
These offerings share a singular objective: ecosystem lock-in. When a consumer’s daily spending, savings, and digital wallet are inextricably linked to their iPhone, the switching costs to move to an Android device or a competing financial institution increase exponentially.
Why Goldman Sachs and Apple Needed a Boost
The partnership between Apple and Goldman Sachs has seen its share of high-profile turbulence, including reports of high default rates and internal friction regarding risk management. While Goldman Sachs has reportedly sought ways to scale back or offload aspects of its consumer lending partnerships, innovative promotional campaigns like "Double Daily Cash" demonstrate that the core product roadmap remains active and aggressive in acquiring high-quality, credit-worthy cardholders.
Furthermore, by targeting the holiday shopping season—a period traditionally dominated by heavy credit card sign-ups from traditional banks like Chase, American Express, and Citi—Apple is positioning its digital-first card as a primary wallet contender against established heavyweights like the Chase Freedom or Citi Double Cash cards.
Official Guidelines and Consumer Disclaimers
As with any major financial product, transparency regarding terms and conditions is paramount. Apple has outlined several critical caveats that every prospective applicant should review:
- Exclusivity Requirement: The double cash-back rate is not automatically applied to standard applications initiated via a general web search or through the iOS Wallet app unless prompted by specific promotional banners. Users must utilize the designated promotional link (learn.applecard.apple/double-your-daily-cash-promo) to guarantee eligibility.
- Merchant Variability: Apple explicitly notes that participating merchant partners and their associated reward structures are subject to change at any time. While Apple and core partners consistently yield the highest tiers, third-party merchants can alter their promotional status.
- Credit Approval Standards: Approval is subject to credit check and financial evaluation. While the Apple Card is renowned for its soft-pull application process (which lets users check their potential credit limit and APR without damaging their credit score prior to formal acceptance), standard creditworthiness criteria apply.
- Immediate Payout Structure: Unlike traditional credit card programs that require users to wait until the closing date of a billing cycle to view or redeem rewards, Daily Cash continues to settle into the user’s account on a daily basis, maintaining the core value proposition of immediate liquidity.
Future Outlook: What This Means for the Future of Apple’s Fintech Strategy
The launch of the Double Daily Cash promotion offers a fascinating lens through which to view the future trajectory of Apple’s financial services division.
Will Temporary Promos Become the Norm?
Historically, Apple has relied on the inherent convenience of its hardware integration and clean user interface to sell products rather than engaging in aggressive cash-back wars with traditional credit card issuers. Standard 2% cash back on Apple Pay purchases was once considered cutting-edge, but as competitors introduce rotating categories, flat 2% cards with no restrictions, and steep sign-up bonuses, Apple had to adapt.
This aggressive holiday push suggests that Apple is increasingly willing to leverage financial incentives to drive user acquisition. If the campaign proves successful in driving massive volumes of new card activations and increased Apple Pay adoption ahead of the December 10 deadline, we may see similar aggressive promotional windows opened during subsequent peak retail periods, such as back-to-school season or spring shopping spikes.
The Broader Ecosystem Impact
Ultimately, a consumer earning 4% to 6% back on purchases funnels substantial transactional data and financial loyalty directly back into Apple’s ecosystem. When those cash rewards are automatically deposited into an Apple Cash card—and subsequently rolled over into an associated high-yield Apple Savings account—Apple effectively creates a closed-loop financial flywheel.
For consumers on the fence about whether to take the plunge into Apple’s financial ecosystem, the window of opportunity is narrow. With applications closing on December 10, prospective cardholders have a limited time to secure a full year of accelerated earnings that effectively redefines the baseline value of digital payments.