Date: September 29, 2026
Author: Saf Malik, Senior Content and Insights Manager
Location: Austin, Texas
Executive Overview
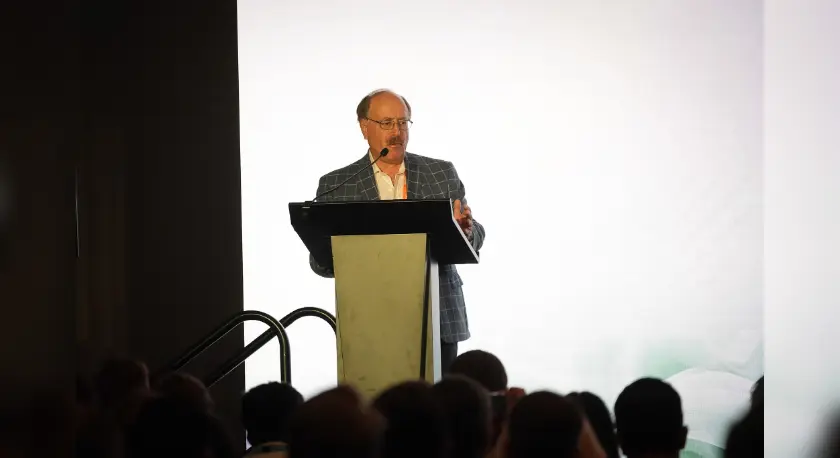
The intersection of digital infrastructure and energy supply has officially reached a critical juncture. At the recent Metro Connect Fall x Datacloud USA 2026 conference in Austin, Texas, industry leaders, financiers, policymakers, and technologists gathered to dissect the forces reshaping the telecommunications and data centre landscapes. Across four intensive days of high-level panels, keynotes, fireside chats, and invitation-only closed-door sessions operating under the Chatham House Rule, one overarching theme dominated every conversation: the race to balance unprecedented AI-driven demand with physical, regulatory, and financial realities.
Texas—and specifically the Electric Reliability Council of Texas (ERCOT) grid—sat squarely at the epicentre of these discussions. With a staggering 474 gigawatts (GW) of large-load interconnection requests currently under review, of which data centres account for an unprecedented 90%, the Lone Star State is serving as the ultimate testing ground for the global digital infrastructure boom.
However, this massive surge in demand has triggered significant friction. A state-ordered audit has temporarily paused new grid approvals, forcing developers, utility providers, and state regulators to grapple with a fundamental question: How much of this projected demand is practically actionable, and how can the grid sustain it without collapsing?
Capacity’s comprehensive in-depth report compiles the definitive insights from Austin, examining the colliding worlds of power generation, fibre-optic networks, capital markets, and off-the-record industry sentiment. From Nvidia’s ambitious $500 billion financing bridge to the evolving bottlenecks in fibre permitting, the digital infrastructure sector is undergoing a profound structural transformation.
Detailed Chronology: Four Days of High-Stakes Discourse in Austin
Day 1: The Power Crunch and the Texas Microcosm
The conference kicked off with a laser-like focus on energy supply constraints. The opening keynotes immediately addressed the elephant in the room: power availability is no longer just a technical hurdle; it is the primary bottleneck dictating where and when the next generation of digital infrastructure can be built.
Industry executives dissected the ERCOT bottleneck during morning panels. The revelation that data centres make up 90% of ERCOT’s 474GW backlog shocked many attendees, illustrating the insatiable power appetite of generative AI workloads. State regulators emphasized that the mandatory audit of these pending interconnections is necessary to filter out speculative grid applications and prioritize projects with genuine execution capability.
Yet, off-the-record discussions during closed-door roundtables revealed deep anxiety among developers. Many warned that extended regulatory pauses could push major capital investments out of Texas and into alternative, potentially less optimal, markets.
Day 2: Capital Markets, Nvidia, and Bridging the Financing Gap
As the conference moved into capital markets and financial strategies, attention shifted toward the macroeconomic structures required to fund the AI revolution.
One of the most talked-about sessions centred on Nvidia’s aggressive $500 billion push designed to bridge a daunting 20-year financing gap. Analysts and financiers debated the long-term viability of private capital stepping in to fund massive, capital-intensive digital infrastructure projects. Traditional project finance models are being stretched to their absolute limits, prompting sovereign wealth funds, private equity giants, and hyperscalers to forge novel public-private partnerships.
Later in the day, veteran industry voice Andy Lipman delivered his signature flashpoints countdown, outlining the regulatory, legal, and operational landmines that deal-makers must navigate over the next 12 to 18 months. Lipman’s insights underscored the complex web of cross-border compliance, antitrust scrutiny, and municipal pushback facing modern digital infrastructure rollouts.
Day 3: The Fibre Frontier and Permitting Paradigms
While power dominated the headlines, Day 3 brought a critical reality check regarding the physical pipes connecting these massive data hubs: fibre networks.
Panelists pointed out a fascinating shift in industry pain points: while power access remains notoriously difficult, permitting has officially overtaken power as the top operational constraint in many key markets. Securing rights-of-way, municipal approvals, and environmental clearances for long-haul and metro fibre routes has become an increasingly tortuous process.
Despite these hurdles, market consolidation and deal-making remain remarkably robust. Data presented at the event highlighted that 41 distinct US fibre deals have been officially recorded so far in 2026. Executives in closed-door sessions noted that while valuations remain high, investors are increasingly discriminating, prioritizing dense urban rings and robust enterprise routes over speculative greenfield builds.
Day 4: Synthesis, Chatham House Insights, and Future Horizons
The final day of Metro Connect Fall x Datacloud USA synthesized the preceding discussions through intensive debriefs and future-casting panels.

Under the Chatham House Rule, senior executives from leading fibre builders and data centre developers spoke with unprecedented candor. Conversations centred on the uncomfortable truths of supply chain dependencies, geopolitical risks affecting semiconductor and optical hardware availability, and the pressing need for talent acquisition in an increasingly specialized technical workforce.
The consensus from the closing sessions was clear: the digital infrastructure sector is no longer operating in a "business as usual" environment. Hyper-growth driven by artificial intelligence demands unprecedented collaboration between utilities, telecom operators, real estate developers, and government regulators.
Supporting Context & Key Metrics
To fully understand the gravity of the discussions in Austin, one must examine the macro-level metrics driving the North American digital infrastructure landscape in 2026:
- 474 GW: The total volume of large-load interconnection requests currently pending review under ERCOT in Texas.
- 90%: The estimated proportion of ERCOT’s pending large-load requests that originate directly from data centre developers preparing for massive AI computing clusters.
- $500 Billion: The scale of Nvidia’s strategic financing push aimed at bridging a 20-year capital investment gap required to sustain next-generation AI infrastructure ecosystems.
- 41 Fibre Transactions: The total number of verified mergers, acquisitions, and strategic investments recorded within the US fibre market during the first three quarters of 2026.
- Permitting vs. Power: A notable shift in developer sentiment indicating that local municipal permitting processes have surpassed raw power availability as the primary bottleneck in select metropolitan fibre deployment corridors.
Official Statements and Industry Perspectives
The urgency of the Austin summit was reflected in the commentary shared across keynotes and panel stages.
Addressing the Texas power dilemma, market analysts noted:
"The sheer volume of applications sitting on ERCOT’s desk is unprecedented in the history of American utility management. We are no longer talking about incremental growth; we are talking about load additions equivalent to entire industrial sectors materializing over a matter of months. The audit is painful, but it is an essential reality check for an industry moving at breakneck speed."
On the capital expenditure front, financial strategists emphasized the collaborative nature of modern digital real estate:
"The traditional silo between power generation, transmission, and data centre development has completely dissolved. If you are a hyperscaler or a co-location provider today, you are essentially an energy company with servers attached. Financing that reality requires entirely new paradigms of capital deployment, risk-sharing, and long-term PPAs (Power Purchase Agreements)."
Regarding the quiet crisis in fibre deployment, infrastructure veterans observed:
"Everyone is talking about megawatts, and rightfully so—you can’t run an H100 cluster in the dark. But once you secure the power, you have to move petabytes of data at the speed of light. If our permitting timelines continue to lag behind our data centre construction timelines, we are going to build the most powerful computing nodes on earth and find ourselves completely disconnected from the rest of the world."
Future Outlook: Looking Ahead to Metro Connect USA 2027
As the dust settles on Austin, the digital infrastructure community is already turning its gaze toward the horizon. The lessons learned at Metro Connect Fall x Datacloud USA 2026 will serve as the strategic playbook for the coming year.
The next major milestone on the industry calendar will be Metro Connect USA 2027, scheduled for February 8, 2027. Celebrating its landmark 25th anniversary, Metro Connect USA stands as the largest executive-level digital infrastructure event in the United States. For a quarter-century, this premier gathering has served as the definitive nexus where senior decision-makers, investors, and operators converge to forge the partnerships that drive the connectivity economy forward.
As the industry prepares for February 2027, the stakes have never been higher. The decisions made in boardrooms, regulatory hearings, and financing syndicates over the next several months will determine whether the United States can successfully build the robust, electrified, and fiber-connected foundation required to support the next era of technological evolution.
To access the complete, unedited in-depth report featuring comprehensive data breakdowns, full speaker rosters, and exclusive Chatham House insights from the Austin conference, download the full publication via Capacity Global.