Executive Overview
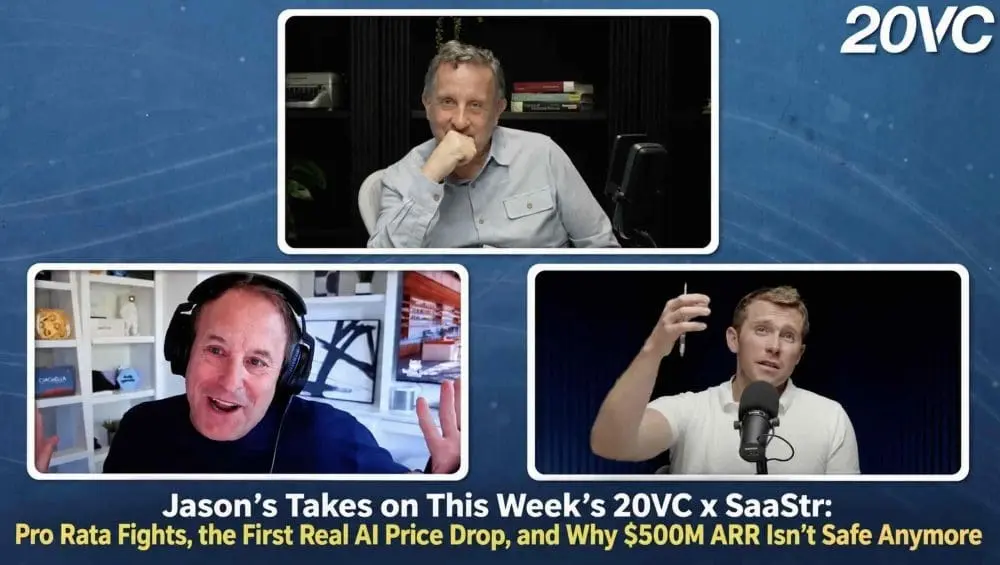
The modern software landscape is defined by an unprecedented duality: explosive decacorn valuations coexisting with a brutal reckoning for mid-market B2B enterprises. According to recent market analysis and insights drawn from the 20VC and SaaStr ecosystems featuring Harry Stebbings and Rory O’Driscoll, the rules of venture capital, enterprise software, and artificial intelligence deployment have fundamentally shifted.
We are witnessing a market where 42 decacorns can emerge in just ten months, and a staggering $870 million Series A can close within 24 days of a company’s launch—yet traditional software companies generating tens or hundreds of millions in Annual Recurring Revenue (ARR) find themselves stranded, unable to clear the dramatically raised bar for an Initial Public Offering (IPO) or secure a lucrative liquidity event.
At the intersection of this turbulence are critical lessons for founders, investors, and operators alike. From legal disputes over cap table waivers to the rapidly collapsing cost of frontier AI models and the structural threats posed by hyper-growth roll-up acquirers, the path forward requires radical adaptation. Capital and attention are concentrating entirely at the extremes: absolute scale and AI-native agility. For everything in between, survival demands a complete operational rewrite.
Detailed Chronology: Key Fault Lines in Venture and Enterprise Tech
1. The Cap Table Wars: When Waivers Turn Litigious
The mechanics of venture financing are under intense scrutiny following high-profile friction between early investors and mega-funds. The dispute involving Valar, Day One, and Quinn Emanuel highlights a recurring hazard in late-stage rounds. When massive institutional funds step in, their term sheets almost universally mandate that existing investors waive their pro rata rights.
The flashpoint occurs when exceptions are made. When a fund asks an entire syndicate to surrender its pro rata privileges while quietly carving out a single allocation for a preferred "strategic" partner, routine friction explodes into legal confrontation.
- The Founder’s Dilemma: Founders must recognize that pro rata rights are priced into seed rounds. Early investors pay higher valuations in exchange for the right to maintain their ownership stakes in subsequent rounds. Stripping these rights later without universal application damages trust.
- The Investor’s Takeaway: If an investor is cut out of a round despite early support, voicing an objection once is appropriate. Beyond that, the cap table belongs to the founder, who must live with their syndicate choices for the next two decades. Endless disputes achieve nothing save for poisoned relationships.
2. The AI Model Layer: Benchmarks vs. Production Reality
The artificial intelligence boom has introduced a dangerous distraction: leaderboard chasing. The release of advanced frontier models—such as the hypothetical Muse Wonder Full—often generates immense buzz due to staggering benchmark scores. However, if a model lacks an accessible API and is locked exclusively within proprietary consumer applications (like Muse Code), its practical utility for B2B developers is zero.
Simultaneously, the foundational economics of AI are experiencing a deflationary shock. The release of models like Haiku 5.5 has driven prompt costs down by up to 90% for workloads under 100K tokens, while offering capabilities approaching higher-tier models like Sonnet. For the first time in two years, overall AI infrastructure costs are declining for many engineering teams, allowing organizations to scale AI processing across entire databases rather than mere samples.
Furthermore, the rise of hyper-focused specialized models like Jev—built strictly for binary decision-making, classification, and routing rather than text generation—demonstrates that founders can offload up to 80% of classification tasks from expensive frontier models to ultra-cheap, highly efficient architectures.
3. Consolidation, Cost-Cutting, and the B2B Liquidity Crunch
As enterprise software faces a sluggish buying environment, corporate strategy is bifurcating into aggressive restructuring and defensive acquisitions.
The acquisition playbook of firms like Bending Spoons—absorbing legacy mainstays such as Evernote, Vimeo, and now Airtable—highlights a harsh reality for startup teams. While media coverage fixates on transaction multiples, the human cost is severe: the vast majority of target company employees face displacement. Founders considering a sale to aggressive cost-cutters must negotiate employee protections upfront, as post-acquisition leverage evaporates overnight.
On the corporate restructuring front, leadership teams are learning that incremental layoffs—such as 5% or 7% reductions—fail to restore organizational velocity and merely compound internal anxiety. Successful turnarounds, such as Cloudflare’s decisive 20% workforce adjustment executed in a single day, prove that deep, singular restructuring is vastly superior to a death of a thousand cuts.
Supporting Context & Metrics: The New Thresholds of Scale
The structural changes reshaping the software industry are quantified by stark shifts in capital allocation and liquidity metrics:
- The IPO Bar Has Tripled: Historically, reaching $500 million in ARR provided a safe, reliable runway to an IPO. In the current market climate, that threshold has likely surged to between $1.5 billion and $2 billion. With mid-market software companies numbering in the hundreds and Big Tech consolidating only a handful per year, traditional public markets are closed to all but the absolute elite.
- The Rise of the AI-First Strategic Exit: As traditional IPO pathways narrow, alternative exits are gaining prominence. The trajectory of companies like TechWolf—which restructured around native AI capabilities before securing a landmark acquisition by SAP—illustrates the blueprint for mid-stage startups seeking liquidity in a cautious macro environment.
- Venture Capital Concentration: The paradox of the current cycle is characterized by extremes: 42 decacorns minted within a ten-month window, and venture rounds crossing nearly $900 million weeks after inception, contrasted against a frozen market for companies lacking category dominance.
Official Perspectives and Expert Analysis
Industry leaders and seasoned investors emphasize that the era of easy software growth is definitively over.
Reflecting on the legal friction between mega-funds and seed investors, market commentators note that heavy-handed tactics by incoming institutions frequently disrupt well-balanced early syndicates. When Sequoia or similar giants enter aggressively, demanding universal pro rata waivers, the integrity of the cap table relies entirely on transparency and equity. Carving out isolated exceptions invites litigation and fractures the founder-investor bond.
On the enterprise AI front, experts warn against the trap of building on consumer-facing novelties. As Rory O’Driscoll and other market analysts point out, relying on infrastructure controlled by tech giants who treat a product category as a secondary feature is a losing bet. B2B founders must instead back dedicated, hyper-focused teams whose entire corporate survival depends on maintaining dominance within a specific niche.
Regarding corporate exits and operational efficiency, the consensus is unequivocal: scale is the ultimate defensive moat. Companies failing to hit decacorn scale or immediate AI-native differentiation must either pivot aggressively toward cash-flow generation or resign themselves to strategic acquisition on the buyer’s terms.
Future Outlook: Navigating the AI-Native Era
The trajectory of the B2B software and venture capital ecosystem over the next several years will be dictated by three core imperatives:
- Embrace AI-Native Workflows Immediately: Startups currently sitting at $100 million in ARR striving for the $300 million milestone cannot rely on legacy playbook tactics. Transitioning to AI-first architectures is no longer a value-add feature; it is a foundational requirement to attract strategic acquirers in lieu of a viable IPO market.
- Optimize Unit Economics Through Falling Inference Costs: With token prices and specialized decision-model costs plummeting, engineering leaders must re-run their workload economics monthly. Transitioning routine classification and routing tasks away from frontier models to hyper-efficient narrow models will preserve capital for core product differentiation.
- Prepare for a Hyper-Consolidated Market: Capital will continue to pool around absolute winners. Founders and investors must manage burn rates, eliminate half-measure restructurings in favor of decisive operational adjustments, and maintain strict alignment across cap tables to withstand ongoing macroeconomic pressures.
Ultimately, scale remains the only safe harbor in the modern technology economy. Those who adapt to the ruthless realities of AI economics and capital concentration will thrive; those caught in the middle must rapidly reinvent their business models or prepare for profound structural consolidation.