By Catie Owen
Published: October 9, 2026
Executive Overview
For decades, the telecommunications industry viewed satellite technology through a specialized, albeit restricted, lens. It was the connectivity tool of last resort—designed to bridge the digital divide in sparsely populated rural expanses, maintain vital links for maritime vessels on open oceans, and supply rudimentary communications to daring expeditions in the most remote corners of the globe. Within the broader architecture of mainstream enterprise networking, satellite occupied a distinct, niche corner: functional, expensive, and largely decoupled from the high-speed data pipelines powering urban centers.
Today, that paradigm has fundamentally shattered. Driven by a convergence of technological breakthroughs, proliferating Low Earth Orbit (LEO) constellations, and an enterprise market desperate for bulletproof operational resilience, satellite communications (satcom) has ascended to a core strategic component of mainstream telecommunications infrastructure. It is no longer just a fallback plan; it has transformed into an indispensable pillar of modern service provider portfolios.
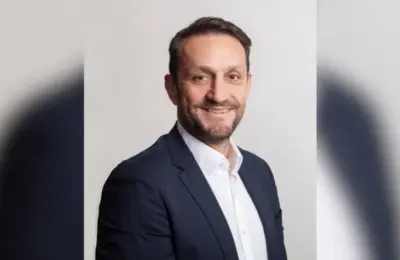
In the lead-up to the landmark 25th-anniversary edition of Capacity Europe 2026, industry leaders are aggressively evaluating how satellite integration redefines enterprise connectivity. Among the foremost voices charting this evolution is Olivier Gommes, Chief Technology and Innovation Officer (CP) at Marlink. As a premier managed network service provider, Marlink has carved out a defining role by partnering with traditional telecom operators to deliver seamless, high-performance satellite and hybrid connectivity solutions.
As satellite officially shifts from a novelty to a critical necessity, communication service providers (CSPs) across the globe are grappling with a complex set of operational challenges: How does modern multi-orbit technology actually function at scale, and how can operators accurately select and deploy the right architectural mix for diverse enterprise clients?
Detailed Chronology of a Paradigm Shift: From Isolated Trials to Enterprise Production
To understand how satellite earned its seat at the core of modern telecoms, one must examine the rapid, almost breathless acceleration of the market over the past several years.
Phase 1: The Era of Isolation (Pre-2024)
Historically, deploying satellite connectivity meant navigating high latency, prohibitive hardware costs, and rigid, single-vendor contracts. Enterprises treated satellite exclusively as an emergency backup link for remote industrial sites—such as oil rigs, mining outposts, and cargo fleets—where terrestrial fiber or fixed wireless was physically impossible to deploy. For major telecom operators, satellite services were outsourced to specialized contractors, remaining completely siloed from core enterprise product lines. Trials were small-scale, isolated, and plagued by bandwidth bottlenecks.
Phase 2: The Multi-Orbit Awakening (2024–2025)
The tipping point arrived with the commercial maturation of Low Earth Orbit (LEO) and Medium Earth Orbit (MEO) constellations. Unlike traditional Geostationary (GEO) satellites sitting thousands of miles away in high orbits, LEO constellations introduced latency figures rivalling terrestrial networks, paired with dramatically increased throughput.
During this window, forward-thinking managed service providers like Marlink began moving satellite integrations out of isolated test labs and into early-stage production environments. Enterprises started demanding hybrid routing architectures—dynamically switching traffic between terrestrial fiber, 5G cellular, and satellite links based on real-time performance metrics. However, the operational overhead remained immense; telcos struggled to manage disparate billing models, complex regulatory frameworks, and rapidly evolving hardware upgrade cycles from multiple space-tech operators.
Phase 3: Mainstream Industrialization & Scale (2026 and Beyond)
Today, satellite connectivity has firmly established itself within large-scale production ecosystems supporting thousands of concurrent enterprise locations worldwide. What was once evaluated through cautious pilot programs is now a board-level imperative.
Service providers are no longer asking if they should offer satellite, but how quickly they can integrate comprehensive multi-orbit portfolios into their core service catalogs. Market awareness has skyrocketed; enterprise buyers are deeply informed about the nuances of LEO, MEO, and GEO constellations, actively demanding unified, resilient networks capable of withstanding unprecedented levels of digital disruption.
Supporting Context & Metrics: The Mechanics of Modern Hybrid Networks
The modern enterprise digital environment is exceptionally complex. Cloud computing, artificial intelligence workloads, distributed workforces, and heavy data analytics require a level of network reliability that traditional terrestrial infrastructure alone can no longer guarantee.
The Interdependency of Digital Infrastructure
According to Marlink’s Olivier Gommes, modern connectivity cannot be managed in an operational vacuum. Network performance, cybersecurity, cloud architecture, IT systems, and application delivery are increasingly interdependent. A tactical decision made in one domain invariably triggers cascading implications across the others.
"Connectivity, network performance, cybersecurity, cloud and IT, and applications are increasingly interdependent, so decisions in one area can have implications across the others," explains Olivier Gommes.
When an enterprise deploys a new cloud-native application, it demands low latency, high throughput, and guaranteed uptime. If a localized fiber cut or subsea cable disruption occurs, the entire business operation risks grinding to a halt. This is where modern satellite integration shines. By utilizing software-defined wide area network (SD-WAN) technologies coupled with multi-orbit satcom links, enterprises can maintain continuous, high-speed operations regardless of physical disruptions on the ground.
Navigating the Multi-Orbit Ecosystem
The current market offers a staggering array of choices. Different constellations, varied orbits (LEO, MEO, GEO), and specialized service models each serve distinct enterprise functions:

- Low Earth Orbit (LEO): Characterized by low latency and high bandwidth. Platforms like SpaceX’s Starlink, Eutelsat OneWeb, and emerging providers like Amazon’s Kuiper project are revolutionizing how real-time applications and LTE/5G backhaul are deployed in the field.
- Medium Earth Orbit (MEO): Offering an optimal balance of coverage area and lower latency, MEO networks excel at delivering high-capacity enterprise trunking and maritime connectivity.
- Geostationary (GEO): Retains its crown for massive broadcast distribution, wide-area regional coverage, and dependable baseline connectivity where ultra-low latency is secondary to absolute coverage footprint.
For communication service providers, navigating this alphabet soup of orbital mechanics can quickly become a logistical nightmare. This complexity has catalyzed the rapid growth of managed network service providers who sit squarely between the space ecosystem and the traditional telecom operator. By acting as technology-agnostic integrators, these partners harmonize multi-vendor networks into a single, cohesive, enterprise-grade service offering.
Official Perspectives: Insights from Marlink’s Olivier Gommes
Ahead of his scheduled appearance at the upcoming Capacity Europe conference in London, Olivier Gommes shared vital insights regarding the shifting expectations of enterprise customers and the strategic pitfalls telcos must avoid.
Evolving Customer Expectations
Enterprise demands have undergone a radical transformation. While remote connectivity remains a cornerstone, the primary drivers today are comprehensive business resilience, instantaneous site deployment, and secure failover mechanisms.
"For telcos, satellite has become something customers increasingly expect to see as part of a connectivity portfolio," Gommes notes. "Enterprise customers are asking about resilience, back-up connectivity, rapid site deployment and extending connectivity into locations where terrestrial services aren’t always practical."
Despite these surging expectations, many traditional telecom operators remain hesitant to absorb the massive technical overhead required to manage multiple satellite operators, keep pace with accelerating technology roadmaps, navigate complex global certification processes, and support diverse customer hardware models. This hesitation creates a strategic vacuum, driving service providers to rely on specialized ecosystem partners.
Avoiding the "Connectivity Trap"
A common, costly mistake made by service providers entering the satellite space is focusing exclusively on the raw connectivity product rather than the sophisticated operational model required to support it at scale.
"A service like Starlink can appear very straightforward initially, but enterprise-scale deployments quickly introduce additional requirements around billing, logistics, network integration, security, installation, support, and service management," warns Gommes.
When scaling to thousands of enterprise sites, the hidden operational burdens—ranging from localized customs clearance for hardware terminals to 24/7 multilingual technical support and unified billing platforms—can quickly overwhelm an uninitiated telco. Gommes strongly advises service providers to partner with established managed service intermediaries who can handle these backstage complexities, allowing telcos to focus on front-end customer relationships and core service delivery without compromising operational excellence.
Future Outlook: Reinforcing the Global Digital Backbone
As the telecommunications industry looks toward the remainder of the decade, the trajectory of satellite technology points toward deeper integration, heightened security, and absolute indispensability.
Subsea Cable Resilience and Network Diversity
Recent global conversations surrounding the vulnerability of international subsea fiber-optic cables have laid bare the urgent need for diverse, independent connectivity paths. Subsea cables remain the backbone of global internet traffic, but physical damage from maritime anchors, seismic activity, or geopolitical sabotage can sever major economic corridors in an instant.
Satellite infrastructure provides the ultimate out-of-band redundancy. By acting as a complementary piece of infrastructure, satellite networks can seamlessly absorb traffic surges during terrestrial outages, ensuring absolute business continuity for financial institutions, healthcare providers, and multinational enterprises.
The Business Opportunity for Telcos
Far from being a peripheral technology, satellite is quickly morphing into a major commercial differentiator. As digital transformation accelerates across Europe and beyond, secure, reinforced, and hybrid telecommunications networks are vital investments for sustainable economic growth.
For communication service providers willing to embrace multi-orbit flexibility and leverage expert managed service partnerships, satellite represents an extraordinary commercial opportunity—one that will soon transition from a strategic advantage to an absolute business prerequisite.
Olivier Gommes will be elaborating on these insights during his participation in the Snapshot Presentations: Key developments shaping Europe’s digital infrastructure panel at Capacity Europe.
Join an estimated 4,000 global decision-makers in London from October 13–15 to connect with industry leaders spanning fiber, data centers, cloud, and AI infrastructure. Register here to secure your place.