Date: October 9, 2026
Author: Catie Owen, Regional Content & Insights Lead
Event Context: Capacity Europe 2026 (London, October 13–15)
Executive Overview
For decades, satellite communications occupied a specialized, often misunderstood corner of the global telecommunications ecosystem. Widely perceived as a last-resort utility, it was deployed almost exclusively to bridge the digital divide in sparse rural regions, maintain navigational links for maritime vessels, or provide rudimentary communications for expeditions into the world’s most extreme and isolated environments. Terrestrial fiber optics and cellular towers remained the undisputed backbone of mainstream enterprise and consumer connectivity.
Today, that paradigm has fundamentally shifted. Driven by a relentless corporate demand for business continuity, the acceleration of multi-orbit satellite constellations, and the limitations of aging terrestrial infrastructure, satellite technology has graduated from a niche fallback to a core strategic pillar of mainstream telecommunications architecture.
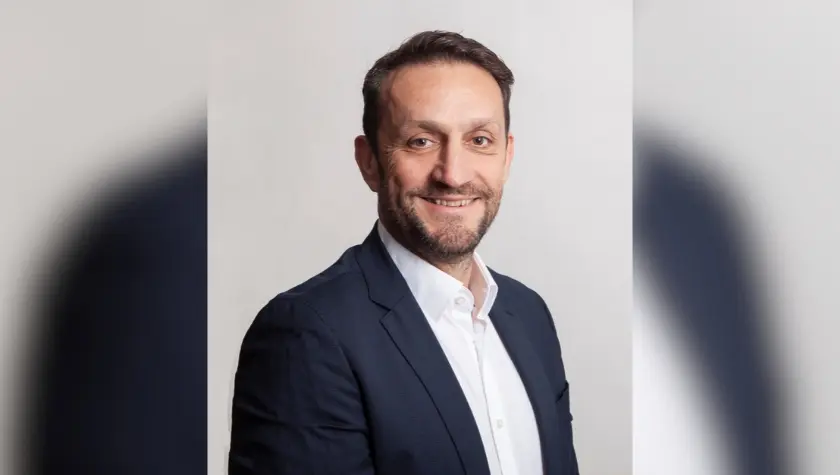
Ahead of Capacity Europe 2026, Olivier Gommes, Chief Technology and Innovation Officer (CP) at Marlink, sat down to discuss this seismic transformation. As a leading managed network service provider specializing in hybrid infrastructure, Marlink has positioned itself at the intersection of traditional telecommunications and cutting-edge aerospace engineering. According to Gommes, the question facing modern telecom operators is no longer if they should integrate satellite into their portfolios, but how to deploy the right multi-orbit solutions to satisfy an increasingly sophisticated enterprise customer base.
Detailed Chronology: The Evolution of Mainstream Satellite
The journey of satellite communications from the fringes of the telecom industry to the boardroom table has accelerated dramatically over the past several years, characterized by three distinct phases of market maturation:
1. The Era of the Niche Utility (Pre-2020)
Prior to the widespread commercialization of Low Earth Orbit (LEO) megaconstellations, satellite connectivity was defined by Geostationary Earth Orbit (GEO) satellites. While GEO satellites provided expansive geographic coverage, they suffered from crippling latency issues, high hardware costs, and limited bandwidth capabilities. Consequently, their deployment was restricted to sectors where terrestrial alternatives were literally non-existent—such as offshore oil rigs, deep-sea shipping fleets, desert mining operations, and remote government outposts. Telecom operators viewed satellite as a low-margin, high-friction service outsourced to specialized vertical integrators.
2. The Hybrid Pivot and Technological Convergence (2020–2024)
As global enterprises accelerated their digital transformation initiatives, cloud adoption, and remote work policies, the vulnerability of purely terrestrial networks became glaringly apparent. Disrptions caused by severed subsea cables, natural disasters, and terrestrial equipment failures drove enterprises to demand true network diversity. During this period, the industry witnessed the rise of Medium Earth Orbit (MEO) and early-stage LEO constellations, which dramatically reduced latency and increased throughput. Telecommunications service providers began experimenting with hybrid network architectures, stitching together fiber, cellular (LTE/5G), and satellite links to guarantee continuous uptime.
3. Mainstream Production and Mass Enterprise Adoption (2025–Present)
By 2025 and moving into 2026, satellite integration crossed the chasm from isolated trials and regional pilot programs into large-scale, enterprise-grade production environments. Today, thousands of corporate locations worldwide utilize hybrid satellite-terrestrial links as a standard component of their Wide Area Network (WAN) strategy. Rather than viewing satellite as a competitor to fiber, modern telecommunications operators embrace it as an indispensable complement, leveraging multi-orbit architectures to deliver rapid site deployments, robust backup redundancy, and ubiquitous enterprise connectivity.
Supporting Context & Metrics: The Changing Demands of the Enterprise Customer
The transition of satellite from an alternative connectivity medium to an infrastructure necessity is fueled by a profound evolution in customer expectations. Modern enterprises operate in a hyper-connected, cloud-first environment where downtime translates directly to lost revenue and reputational damage.
According to insights shared by Marlink, enterprise inquiries regarding satellite integration are no longer driven solely by geographical isolation. Instead, they center on three core pillars:
- Resilience and Redundancy: Corporations demand automated failover systems. If a primary fiber link is severed, traffic must reroute instantly through an independent satellite path without interrupting mission-critical applications.
- Rapid Site Deployment: In industries such as construction, retail pop-ups, defense, and emergency response, waiting weeks or months for terrestrial fiber installation is commercially unviable. Satellite terminals enable high-speed network activation in a matter of hours.
- Extended Reach: Organizations operating sprawling, decentralized campuses or remote logistics corridors require uniform security and performance standards that extend far beyond the reach of traditional metropolitan fiber grids.
However, this growing demand has created an operational paradox for traditional telecommunications operators. While telcos recognize that customers expect satellite capabilities as standard within a modern service portfolio, they are frequently ill-equipped to manage the profound technical complexity of the modern aerospace landscape.
Managing multiple satellite operators, navigating diverse technology roadmaps, handling complex hardware certifications, and supporting disparate billing models introduces significant operational overhead. This friction has created a lucrative market space for managed network service providers like Marlink. Operating between the satellite ecosystem and the telecom service provider, companies like Marlink aggregate diverse networks and technologies into a single, unified, and easily manageable service wrapper.
Official Statements and Industry Insights
Reflecting on the shifting market dynamics, Olivier Gommes emphasized the necessity for service providers to adopt a holistic approach when evaluating connectivity options.

"For telcos, satellite has become something customers increasingly expect to see as part of a connectivity portfolio," Gommes explained. "Enterprise customers are asking about resilience, back-up connectivity, rapid site deployment and extending connectivity into locations where terrestrial services aren’t always practical."
Gommes noted that the sheer abundance of modern options—spanning multiple orbital regimes, constellations, and service models—means that strategic flexibility has never been more important for service providers. However, he warned against falling into the trap of viewing connectivity in an operational vacuum.
"Connectivity, network performance, cyber security, cloud and IT, and applications are increasingly interdependent, so decisions in one area can have implications across the others," Gommes cautioned.
A recurring pitfall for telecom operators entering the satellite space is focusing too narrowly on the connectivity hardware itself while ignoring the operational lifecycle behind it.
"A service like Starlink can appear very straightforward initially, but enterprise-scale deployments quickly introduce additional requirements around billing, logistics, network integration, security, installation, support, and service management," Gommes observed.
Because modern enterprise customers expect these operational requirements to be handled seamlessly as a standard part of their service level agreements (SLAs), Gommes advocates for partnerships with managed service specialists who can absorb the backstage complexity, allowing telcos to focus on front-end customer experience and relationship management.
Future Outlook: The Next Horizon for Satellite and Digital Infrastructure
As the telecommunications sector looks toward the remainder of the decade, the integration of satellite infrastructure into the broader digital economy is set to deepen even further. Several macro-trends will define the evolution of the market:
The Multi-Orbit Expansion
The maturation of advanced LEO constellations—led by established players like Starlink, the continued global expansion of OneWeb, and the impending commercial rollout of Amazon’s Project Kuiper—is democratizing high-speed, low-latency broadband. Gommes highlights that these emerging LEO networks will play a critical role in reinforcing and extending LTE and 5G cellular links, ensuring that mobile operators can maintain high-performance backhaul even in the most challenging topography.
Securing the Physical Layer: Subsea and Terrestrial Resilience
Recent vulnerabilities and disruptions affecting global subsea fiber-optic cables have underscored the structural fragility of purely terrestrial international backbones. Industry leaders increasingly recognize that true network security requires independent, non-terrestrial diversity paths. Satellite infrastructure provides an essential fail-safe, ensuring business continuity for global data flows even when physical conduits are compromised.
The Business Opportunity for Telcos
Far from being a threat to traditional telecommunications business models, satellite represents a profound commercial growth engine. As digital transformation accelerates across European enterprises and global markets, the demand for secure, reinforced, and ubiquitous telecommunications networks will only intensify. Operators that successfully integrate multi-orbit satellite solutions into their core offerings will be uniquely positioned to capture high-value enterprise accounts.
Connect at Capacity Europe 2026
Olivier Gommes will elaborate further on these strategic insights during his participation in the Snapshot Presentations: Key developments shaping Europe’s digital infrastructure panel at Capacity Europe 2026.
The landmark 25th-anniversary edition of the event will convene an estimated 4,000 global decision-makers in London from October 13 to 15, 2026. Industry leaders spanning the entire digital infrastructure ecosystem—including representatives from fiber optics, data centers, cloud computing, and artificial intelligence—will gather to forge partnerships, debate market trends, and chart the future of global connectivity.
Industry professionals interested in shaping the next era of telecommunications infrastructure can register to attend Capacity Europe 2026.