Published: September 29, 2026
Reading Time: ~6 minutes
Author: Global Infrastructure & Telecommunications Desk
Executive Overview
As the global telecommunications and data center landscapes undergo a tectonic shift driven by the exponential rise of artificial intelligence (AI), the foundational layers of the internet are facing unprecedented demands. While headlines frequently capture the astronomical capital expenditure pouring into specialized compute hardware—such as Graphics Processing Units (GPUs)—and massive, hyperscale data center construction sites, a vital, less-visible component remains the true lifeblood of the modern digital economy: the high-capacity global IP network.
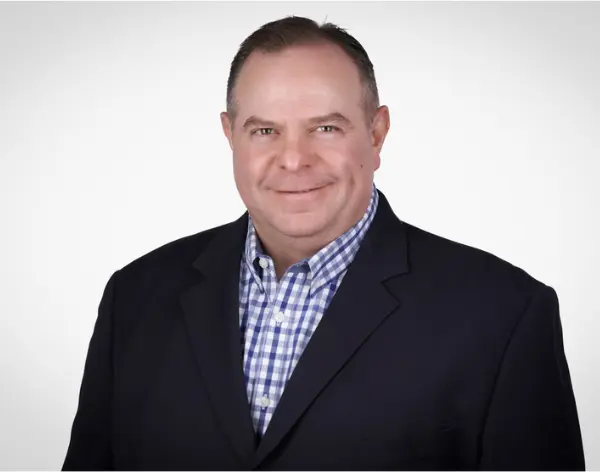
In an extensive industry briefing, Michael Wheeler, Executive Vice President of the Global IP Network division at NTT DATA, offered a comprehensive look into the converging trends, infrastructure bottlenecks, and strategic priorities defining the digital landscape in late 2026. Wheeler posits that while IP networks have historically functioned as the "unsung heroes" of the digital ecosystem, they are rapidly transitioning into the digital "spinal cord" necessary to interconnect increasingly distributed workloads.
This article explores Wheeler’s insights across several key operational fronts: the bifurcation of AI workloads between heavy training and rapid inference; the strategic deployment of network footprints versus high-quality connectivity; regional growth patterns led by the Asia-Pacific (APAC) market; and the escalating arms race surrounding network security, resilience, and AI-driven cyber threats.
Detailed Chronology: The Evolution of the AI-Driven Network
The integration of AI into enterprise and consumer applications has not happened overnight; rather, it represents the culmination of years of escalating data demands that have forced tier-one network operators to fundamentally rethink architecture, port capacities, and edge strategies.
Phase 1: The Compute Boom and Infrastructure Strain (2023–2024)
In the early phases of the generative AI boom, the primary industry bottleneck was physical compute. Enterprises and hyperscalers scrambled to secure scarce silicon, leading to massive investments in data center footprints optimized for high-density power and cooling. During this period, networks primarily focused on scaling internal data center fabrics and expanding core trans-oceanic and trans-continental trunk lines to move unprecedented volumes of raw data between training clusters.
Phase 2: The Distributed Workload Reality (2025)
By 2025, the conversation shifted from localized training clusters to distributed architectures. AI models were no longer residing in a single mega-facility; instead, data, training pipelines, and inference engines were scattered across multiple cloud providers, regional data centers, and enterprise private clouds. This evolution highlighted a critical vulnerability: without high-capacity, ultra-low-latency IP backbones connecting these fragmented islands of compute, the grand promise of enterprise AI would stall due to transit bottlenecks.
Phase 3: The Edge and Inference Explosion (2026 and Beyond)
Entering late 2026, the industry is witnessing a profound transition toward real-time deployment and inference. As Wheeler notes, AI workloads are now starkly divided into two distinct buckets: ongoing model training and the real-time application of that training via inference. While training demands massive, sustained bandwidth over core networks, inference is intrinsically tied to user proximity, creating immediate, highly unpredictable pressure points at the network edge.
Supporting Context & Metrics: Where the Pressure Points Lie
To understand the operational challenges facing tier-one operators today, one must analyze where network stress is accumulating. According to Wheeler, the industry is experiencing a structural migration of pressure from core subsea and terrestrial infrastructure outward toward metro and regional markets.
Training vs. Inference: The Dual-Bucket Challenge
- Model Training: Characterized by predictable, massive, bulk-data transfers over long periods. These workloads require high-capacity ports (such as the surging demand for 400G and emerging higher-speed standards) connecting major data center hubs.
- Model Inference: Characterized by bursty, latency-sensitive, and highly unpredictable traffic profiles. Because inference directly serves end-users, applications, and IoT devices, it must occur as close to the user as possible.
This operational reality places intense demands on metropolitan and regional exchange points. Network operators can no longer rely solely on massive core pipes; they must ensure that regional peering points and edge routing nodes possess the agility and capacity to handle sudden spikes in micro-transactions without introducing jitter or latency.
Footprint vs. Quality: The Tier-One Strategy
A perennial debate among telecommunications executives centers on network reach: Is it better to boast the largest possible footprint of Points of Presence (PoPs), or should the focus remain strictly on high-quality connectivity in high-density locations?
Wheeler addresses this trade-off by drawing a clear distinction between business models:
- Mass-Market Carriers: Consumer and business ISPs operating at a national or regional level often benefit from a sprawling footprint, embedding themselves in numerous local facilities to capture localized subscriber bases.
- Global IP Backbone Providers (NTT DATA): For a tier-one global player serving internet-centric businesses, cloud providers, and content delivery networks (CDNs), ubiquity for its own sake is economically inefficient. The strategic imperative is to secure presence precisely where internet traffic is most densely exchanged—maximizing throughput and performance where demand is concentrated rather than chasing speculative coverage.
"It doesn’t matter how many sites you’re in or where you are if you’re losing money," Wheeler emphasizes, underlining the importance of aligning infrastructure investment with sustainable capital returns and long-term enterprise strategy.
Official Statements and Strategic Insights
During the briefing, Wheeler detailed several key performance indicators regarding NTT DATA’s global footprint, customer demand vectors, and evolving expectations surrounding resilience and security.
Geographic and Segment Growth
NTT DATA’s global IP backbone is currently registering robust, multi-regional demand, with standout performance across the Asia-Pacific (APAC) corridor.
- APAC Momentum: The region has emerged as a primary growth engine, marked by a dramatic uptick in customer requests for high-capacity 400G ports, which in turn are driving exponential traffic growth across regional peering architectures.
- Western Markets: Concurrently, North America and Europe maintain strong, steady baselines of enterprise and hyperscale demand.
- Key Vertical Drivers: Content Delivery Networks (CDNs) remain massive, baseline traffic generators. However, the fastest-accelerating demand segments now include major cloud operators scaling out dedicated AI initiatives and the global gaming sector, both of which demand uncompromising throughput and low latency.
Redefining Resilience in a Hybrid Work Era
The operational definition of "network resilience" has undergone a permanent shift since the global disruptions of the COVID-19 pandemic and the subsequent entrenchment of hybrid work models.
Wheeler points out that enterprises now rely on continuous, uninterrupted network availability not merely for auxiliary communications, but as the foundational operating system of daily business. Workers distributed across home offices, regional hubs, and corporate headquarters require seamless, zero-downtime access to cloud-based applications, SaaS platforms, and centralized AI resources. Consequently, network redundancy is no longer a luxury feature for mission-critical financial institutions—it is an absolute baseline expectation for all enterprise segments.
The Cyber Security Arms Race
Security remains top-of-mind as threat actors increasingly weaponize artificial intelligence to orchestrate automated, highly sophisticated cyberattacks, including massive distributed denial-of-service (DDoS) campaigns and intelligent network probing.
However, Wheeler remains optimistic regarding the industry’s defensive posture. Just as bad actors are leveraging AI to launch attacks, security architects and network operators are deploying increasingly sophisticated, AI-driven mitigation tools. This creates an ongoing technological cat-and-mouse race, but one where modern automated defense systems provide the requisite agility to neutralize emerging threats before they compromise core backbone integrity.
Future Outlook: The Next Horizon for Global Connectivity
As the telecommunications sector looks beyond 2026, the convergence of AI, edge computing, and ultra-high-capacity networking will continue to redefine the parameters of digital infrastructure.
- The Rise of 400G and Beyond: As 400G ports transition from high-end offerings to mainstream operational standards in regions like Asia-Pacific, North America, and Europe, planning for the next generation of terabit-scale connectivity is already underway.
- Edge-Core Synergy: The pressure of AI inference will necessitate deeper collaboration between data center developers and tier-one network operators, ensuring that edge facilities are seamlessly wired into high-performance global backbones.
- Autonomous Network Operations: With security threats and traffic management growing too complex for purely manual oversight, the industry will lean further into self-healing, AI-managed network fabrics that can autonomously route traffic around congestion points and mitigate cyber incursions in real-time.
Ultimately, as Michael Wheeler underscores, the success of the modern digital economy relies not on any single isolated component, but on the harmonious integration of compute, storage, software, and the resilient "spinal cord" of global IP networks working in unison.