Executive Overview
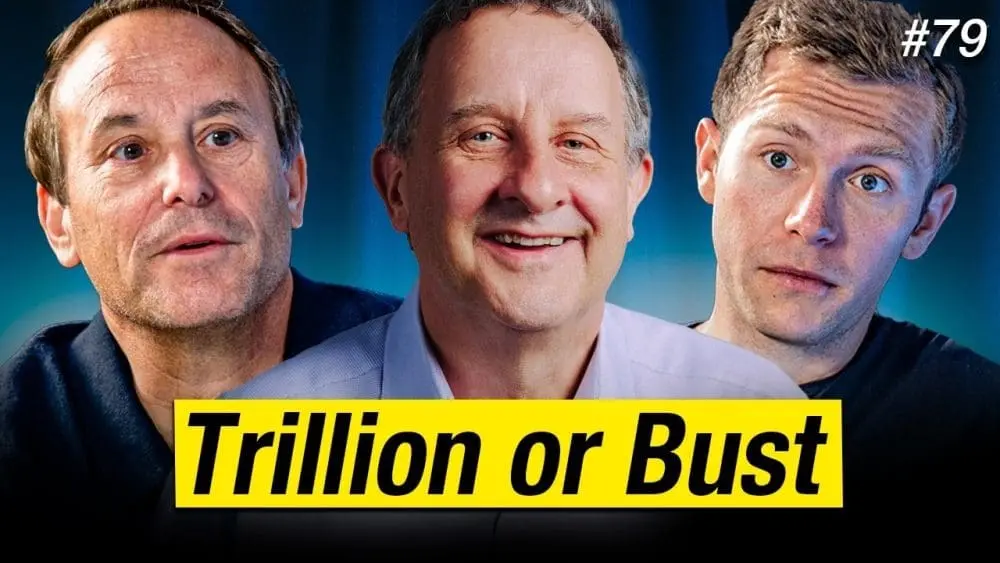
The venture capital landscape is undergoing a profound structural contraction. According to recent insights from industry heavyweights Harry Stebbings, Rory O’Driscoll, and Jason Lemkin, capital is concentrating into fewer names than at any point in recent history. Mega-funds managing upwards of $5 billion are trapped in a mathematical imperative: to matter to their investors, they must secure billion-dollar positions in every deal they back. Consequently, great businesses outside the current hype cycles struggle to secure even an initial meeting.
At the same time, the broader technology ecosystem is grappling with severe macroeconomic corrections. Neoclouds like CoreWeave are facing severe debt and valuation pressures as investors question the sustainability of heavy capital expenditures amid fluctuating demand. Conversely, generative AI flagbearers like Anthropic and infrastructure providers like Modal continue to shatter growth ceilings, even as public and private market valuations face intense scrutiny.
This article explores the core themes emerging from the modern venture and tech ecosystems: the vanishing middle tier of venture funding, the rise of "build-to-prod" software as the definitive category of the AI era, and the seismic shifts occurring across public and private valuations.
Detailed Chronology & Market Analysis
1. The Venture Capital Squeeze: When Top-Decile Numbers Go Unnoticed
The disconnect between fundamental business performance and venture capital availability has reached a fever pitch. Harry Stebbings opened a recent industry discussion highlighting a company generating $20 million in Annual Recurring Revenue (ARR), growing at 600% to 700% annually, maintaining strong profitability, and backed by an elite team—yet facing absolute silence from institutional venture capitalists.
- Jason Lemkin’s Perspective: Lemkin noted a similar phenomenon within his own networks, citing early-stage companies raising modest seed rounds and intentionally choosing never to raise institutional capital again. Despite sending monthly updates showcasing 15% to 18% month-over-month growth, founders are met with indifference. Capital is hyper-concentrated in a tiny fraction of companies, defying the historically herd-driven nature of venture.
- Rory O’Driscoll’s Perspective: O’Driscoll offered a nuanced counter-analysis, pointing out that capital is not necessarily vanishing from the ecosystem entirely; rather, it is being diverted into capital-intensive, high-risk frontiers such as space-based data centers and quantum computing. The true squeeze is hitting traditional vertical software, plagued by an unstated fear that foundational AI models will cannibalize entire application categories.
- Tactical Advice for Founders: Founders operating outside hot AI hype cycles must revert to historical networking strategies. Securing top-tier funding now requires meeting dozens of prospective investors until a firm recognizes an outlier asset priced at an attractive valuation relative to its raw performance.
2. The $5 Billion Fund Dilemma: The Mathematics of Mega-Funds
The narrowing scope of venture investments is driven primarily by fund sizing. Mega-funds exceeding $5 billion in capital commitments face an unforgiving economic reality: a $2 billion exit simply does not move the needle.
Unless a fund commands a majority stake, achieving a billion-dollar return from a single portfolio company requires astronomical enterprise outcomes. Investment committee memos at top-tier firms routinely treat a billion-dollar gain as a conservative downside scenario, reserving their primary upside models for outcomes exceeding $25 billion. However, historical data suggests that the global technology sector produces only 10 to 20 "decacorns" per decade. The current market pricing behavior assumes an unsustainable divergence from historical norms.
3. CoreWeave and the Vulnerability of Neocloud Infrastructure
Market sentiment toward AI infrastructure experienced a dramatic shock as neocloud provider CoreWeave faced significant downward pressure. Trading metrics showed substantial single-session declines, bonds trading at distressed yields, and widening default-swap spreads.
- The Neocloud Risk Profile: Neoclouds occupy the riskiest echelon of the AI trade. They rely heavily on debt-financed capital expenditure to underwrite hyper-growth. If demand growth slows even marginally, or if capital expenditures outpace monetization, these businesses lack the defensive margins of traditional SaaS companies.
- Asset Tiering: Industry analysts categorize neoclouds and specialized capacity providers as "B-tier assets" compared to foundational silicon giants like Nvidia. While Nvidia commands irreplaceable technological moats, neoclouds and secondary capacity renters remain acutely sensitive to macroeconomic shocks and fluctuations in enterprise AI adoption rates.
4. Anthropic’s Scale and the Public Market Horizon
Anthropic continues to post staggering financial metrics, reporting a third-quarter revenue run rate reaching $16.8 billion—a dramatic leap from previous quarters—accompanied by adjusted gross margins estimated near 85%. Despite these figures, preliminary discussions ahead of anticipated public offerings have valued the enterprise around $1.5 billion, reflecting cautious public market sentiment regarding developer loyalty and intense competitive pressures from open-weight models and rival labs.
5. Replit, Vibe Coding, and Price Sensitivity
Replit’s strategic shift in defaulting to OpenAI models—driven by significant cost efficiencies for comparable output quality—underscores the hyper-competitive economics of the application layer. Companies generating substantial ARR through developer platforms operate with extreme cost sensitivity. Rather than exhibiting blind brand loyalty to any single foundational model provider, platforms are building intelligent routing systems to optimize token margins, signaling a mature and pragmatic approach to AI integration.
Supporting Context & Metrics
To contextualize the current macroeconomic and venture climate, consider the following structural metrics shaping the technology sector:
- Fund Concentration: A vast majority of late-stage venture capital is now captured by fewer than 25 dominant institutional firms globally.
- AI Infrastructure Capex: Leading AI labs and cloud providers have collectively committed tens of billions of dollars to data center expansion, placing unprecedented leverage on silicon manufacturers and specialized energy grids.
- Secondary Liquidity: Private market tender offers (such as those observed at Anduril valuing the defense tech leader near $90 billion) indicate that private liquidity events are increasingly serving as alternatives to immediate public debuts.
Official Statements & Industry Commentary
"If you are raising a $5 billion-plus fund, you have to have billion-dollar positions in everything. My final question to the investment committee is always: ‘How are we going to get at least a $1 billion position out of this?’"
— Harry Stebbings, Venture Capitalist and Podcaster"The neoclouds will always be the riskiest part of the AI trade. They underwrite high growth with heavy capex and lots of debt. Grow too slowly and customers leave; grow too fast and any demand slowdown sinks you."
— Rory O’Driscoll, Partner at Scale Venture Partners"Build-to-prod is the single most important category in software today. Generation frameworks are solved enough. The time and engineering effort required to make AI-generated code production-ready is where the true bottleneck—and opportunity—lies."
— Jason Lemkin, Founder of SaaStr
Future Outlook
As the venture ecosystem matures through the back half of the decade, several clear trajectories are forming:
- The Rise of "Build-to-Prod": As foundational code generation tools (such as Cursor and Claude Code) saturate the market, the primary friction point for engineering teams has shifted from code creation to code review, testing, sandboxing, and production deployment. Startups focusing on the build-to-prod lifecycle are positioned to capture outsized strategic value.
- LP Capital Recycling: With mega-entities like SpaceX, Anthropic, and potential upcoming public listings generating substantial liquidity for institutional Limited Partners (LPs), recycled capital is expected to re-enter the venture ecosystem, injecting fresh momentum into early-stage funding markets.
- Maturation of the Software Holding Company: Models pioneered by firms like Bending Spoons—focusing on long-term portfolio holding strategies rather than traditional venture flips—will face the ultimate test of durability as digital assets age across extended market cycles.