London, UK — In the rapidly evolving landscape of global telecommunications, few paradigm shifts have been as swift or profound as the elevation of satellite technology. Once siloed as a specialized tool for maritime vessels, isolated rural outposts, and perilous expeditions into the farthest corners of the globe, satellite communications have definitively shaken off their niche status. Today, they stand tall as a critical, strategic pillar of mainstream telecommunications infrastructure, reshaping how service providers architect resilience, redundancy, and ubiquitous coverage.
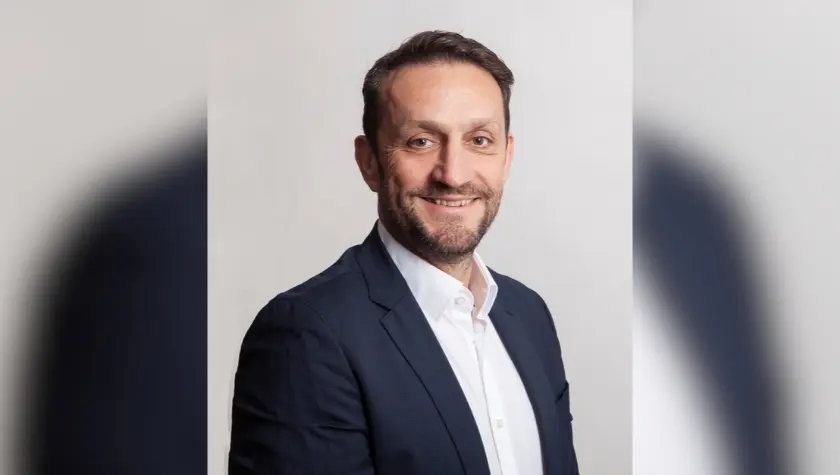
Ahead of the highly anticipated Capacity Europe conference, Olivier Gommes, Chief Technology and Innovation Officer (CP) at Marlink, sat down to discuss this seismic industry transformation. As a leading managed network service provider renowned for crafting connectivity resilience through strategic telco partnerships, Marlink occupies a front-row seat to the modern communications revolution.
As satellite transitions decisively from a luxury alternative to an operational necessity, telecommunications operators worldwide face a pressing question: How does this rapidly maturing technology operate within hybrid ecosystems, and how can providers select the precise architecture required to meet diverse enterprise demands?
Executive Overview
The convergence of traditional terrestrial networks and multi-orbit satellite constellations has fundamentally redefined enterprise expectations. Where once a standard fiber-optic line or local cellular tower was considered the alpha and omega of business connectivity, today’s digital-first enterprises demand absolute continuity. They require networks that can withstand physical disruptions, scale instantaneously, and reach deep into unserved or underserved geographies without missing a beat.
According to Marlink’s Olivier Gommes, this evolution has forced telecom operators to rethink their core service portfolios. Satellite is no longer viewed as an isolated backup mechanism deployed only when all else fails. Instead, it has been integrated directly into mainstream service catalogs, driven by an explosion of enterprise use cases centered around ultra-reliable low latency, rapid site deployment, and holistic business continuity.
However, managing this multi-layered technological ecosystem is no small feat. The complexity of modern satellite constellations—ranging from traditional Geostationary Earth Orbit (GEO) to Medium Earth Orbit (MEO) and the explosive rise of Low Earth Orbit (LEO) networks—presents massive operational hurdles. Telecom operators are increasingly hesitant to absorb the administrative, logistical, and technical overhead required to manage multiple satellite vendors, billing models, and certification pathways.
Consequently, the industry is witnessing a structural shift toward managed service providers (MSPs) like Marlink. By sitting between the complex satellite ecosystem and the downstream service provider, companies like Marlink abstract away the backend friction, delivering a single, cohesive, highly integrated service offering.
Detailed Chronology: The Accelerated Shift of Satellite Integration
To understand how satellite technology achieved mainstream ubiquity, one must examine the rapid pace of change over the preceding 24 months.
The Trial and Pilot Era (Pre-2025)
Historically, telecommunications operators viewed satellite communications with cautious curiosity. Pilots were typically small-scale, localized, and restricted to isolated deployments where terrestrial infrastructure was economically unviable. Enterprises treated satellite links as expensive, high-latency contingencies prone to bandwidth throttling and weather disruptions. Integration with existing IT stacks was rudimentary, and the technology remained largely detached from the broader digital transformation narratives dominating boardrooms.
The Scaling and Production Phase (2025–2026)
The past year marked a distinct inflection point. Satellite technology rapidly graduated from isolated field trials into large-scale, enterprise-grade production environments supporting tens of thousands of simultaneous locations worldwide. Telecom operators began actively embedding satellite architecture directly into their long-term infrastructure strategies.
Concurrently, market awareness underwent a massive spike. Enterprise customers and channel partners became far more sophisticated, moving past basic connectivity inquiries to actively evaluate how multi-technology, multi-orbit networks could work in tandem. This rising awareness brought genuine excitement to the market, fueled primarily by the aggressive deployment and commercialization of next-generation LEO constellations. With service expansions from major players like Starlink, OneWeb, and the impending arrival of Amazon’s Project Kuiper, satellite capacity has proven instrumental in providing robust, high-speed backhauls capable of reliably supporting modern LTE 4G and 5G rollouts.
Supporting Context & Metrics: Navigating the Complexities of Multi-Orbit Infrastructure
The modern enterprise connectivity matrix is deeply interdependent. As Gommes notes, network performance, advanced cybersecurity protocols, cloud infrastructure, IT services, and mission-critical applications can no longer be managed in silos. A strategic decision made in one domain invariably triggers cascading implications across the others.
+-----------------------------------------------------------------+
               THE INTERDEPENDENT DIGITAL ECOSYSTEM
+-----------------------------------------------------------------+
       [Cloud & IT] <-----> [Cybersecurity] <-----> [Applications]
            ^                      ^                     ^
            |                      |                     |
            +----------------------+---------------------+
                                   |
                                   v
             [Multi-Orbit Satellite & Terrestrial Network]
The Multi-Orbit Landscape
Today’s enterprise customers are no longer looking for a one-size-fits-all solution; they demand a nuanced balance of resilience, stringent security, and elite application performance. The market currently offers an unprecedented array of choices:
- Geostationary Earth Orbit (GEO): Providing vast coverage footprints and high broadcast efficiency, ideal for wide-area multicast and foundational backup.
- Medium Earth Orbit (MEO): Offering a balanced compromise between coverage area and latency, highly favored for maritime and energy sectors.
- Low Earth Orbit (LEO): Characterized by exceptionally low latency, high throughput, and rapid deployment capabilities, transforming real-time cloud access in remote areas.
Because each orbit and constellation serves a unique purpose, flexibility has become the ultimate currency for service providers. Marlink, for instance, operates with strict technology and operator agnosticism. By refusing to tie themselves to a single constellation or orbital architecture, such providers can analyze customer challenges on a strictly case-by-case basis, engineering bespoke solutions that blend terrestrial fiber with multi-orbit satellite assets.

Avoiding the Operational "Weeds"
A frequent pitfall for telecom operators entering the satellite space is hyper-focusing exclusively on the raw connectivity product while ignoring the dense operational model required to support it at scale.
As Gommes cautions, a service like Starlink or another LEO solution may appear deceptively simple during initial evaluations. However, enterprise-scale deployments introduce a labyrinth of complex downstream requirements:
- Global billing and multi-currency revenue reconciliation.
- Complex hardware logistics and international customs compliance.
- Seamless software-defined network integration (SD-WAN).
- Rigorous cybersecurity compliance and end-to-end encryption.
- On-site installation, ongoing technical support, and comprehensive service-level management (SLAs).
When enterprise customers demand these rigorous operational standards as baseline expectations, operators risk damaging their brand equity if they attempt to manage platform complexities entirely on their own. Partnering with specialized managed service providers allows telecom companies to offload backend friction while maintaining pristine customer relationships.
Official Statements and Industry Insights
Reflecting on the broader telecommunications ecosystem, Olivier Gommes emphasizes that satellite infrastructure is no longer merely a fail-safe; it is an active protector of global network integrity.
"For telcos, satellite has become something customers increasingly expect to see as part of a connectivity portfolio," Gommes explained during his pre-event briefing. "Enterprise customers are asking about resilience, back-up connectivity, rapid site deployment, and extending connectivity into locations where terrestrial services aren’t always practical."
Furthermore, Gommes points to ongoing global discussions regarding subsea cable resilience as a primary driver for satellite adoption. Subsea cables, while massive carriers of intercontinental data, remain vulnerable to physical disruptions, seismic events, and geopolitical friction points. Satellite infrastructure provides an immediate, highly diverse, and independent connectivity path that reinforces terrestrial networks.
"Connectivity, network performance, cyber security, cloud and IT, and applications are increasingly interdependent, so decisions in one area can have implications across the others," Gommes added, underscoring the necessity for mindful, holistic architectural planning. "The level of interest we see around new LEO constellations and emerging technologies demonstrates just how mainstream the conversation has become."
Future Outlook: The Indispensable Role of Satellite in European Infrastructure
As the European digital economy accelerates, the demand for secure, reinforced telecommunications networks will only intensify. Business-centric regions across Europe are waking up to the reality that a single point of failure in their connectivity chain can spell operational disaster.
Looking ahead over the next several years, industry experts project several key trends:
- Mainstream Enterprise Adoption: Strong, continuous uptake of satellite connectivity for core enterprise sites, particularly where business continuity, disaster recovery, and rapid branch deployment are paramount.
- Hybrid Integration: Deeper integration of software-defined networking (SD-WAN) with multi-orbit satellite paths, allowing automated, real-time traffic steering between fiber and space-based assets based on latency and throughput requirements.
- Subsea and Terrestrial Reinforcement: Increased utilization of satellite backhauls to safeguard critical infrastructure against subsea cable cuts and localized terrestrial grid failures.
- Monetization Opportunities for Telcos: Telecom operators who embrace satellite integration as an agile, value-added service portfolio will unlock significant new revenue streams, transforming potential technological disruption into a formidable business advantage.
Ultimately, satellite technology has graduated from the fringes of telecommunications to become an indispensable pillar of modern digital infrastructure. Ignoring its potential is no longer an option for forward-thinking service providers.
Join the Discussion at Capacity Europe 2026
Olivier Gommes will elaborate further on these critical insights during his participation in the Snapshot Presentations: Key developments shaping Europe’s digital infrastructure panel at Capacity Europe, alongside a distinguished roster of global digital infrastructure experts.
The milestone 25th-anniversary edition of Capacity Europe brings together an estimated 4,000 decision-makers, executives, and innovators in London from October 13 to October 15, 2026. Attendees will have the unique opportunity to connect directly with industry leaders across the entire digital ecosystem, spanning fiber optics, hyperscale data centres, cloud computing, and AI infrastructure.
To secure your place among the industry’s foremost leaders, registration is open via the Capacity Europe Official Registration Portal.