By Catie Owen
Published: October 9, 2026
Executive Overview
For decades, the satellite communications industry occupied a quiet, specialized corner of the global telecommunications ecosystem. Traditionally viewed as a connectivity tool of last resort, it was deployed almost exclusively in isolated maritime endeavors, austere rural landscapes, and expeditions traversing the planet’s most inhospitable terrains. Terrestrial fiber-optic cables and cellular networks held an unshakeable monopoly over urban, high-density, and enterprise-grade connectivity, leaving satellite as a niche utility with high latency, limited bandwidth, and specialized hardware requirements.
Today, that paradigm has fundamentally shattered. Driven by a surge in demand for network resilience, rapid site deployments, and the explosive rise of multi-orbit constellations—including Low Earth Orbit (LEO) networks like Starlink, OneWeb, and emerging platforms like Amazon’s Project Kuiper—satellite has undergone a radical metamorphosis. It is no longer just an alternative to terrestrial systems; it is a critical, foundational pillar of mainstream telecommunications infrastructure.
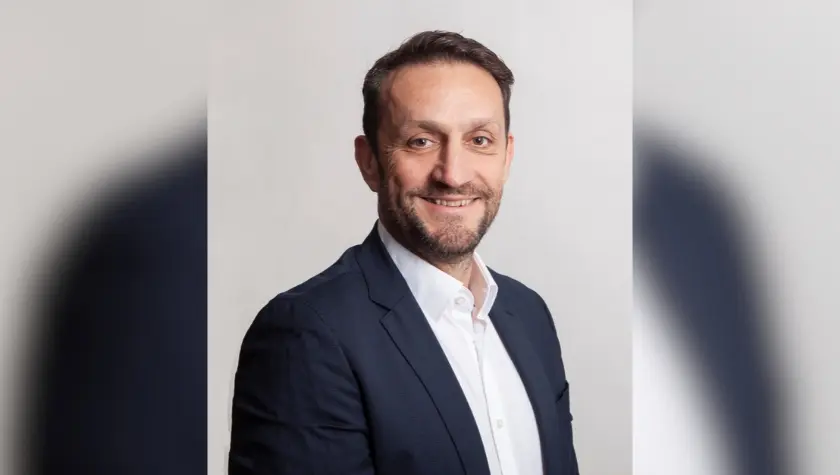
Ahead of Capacity Europe 2026, Olivier Gommes, Chief Technology and Innovation Officer (CP) at managed network service provider Marlink, sat down to discuss this seismic shift. As telcos and enterprise customers alike grapple with the escalating complexities of modern digital infrastructure, satellite technology has emerged as a central catalyst for business continuity, network diversification, and mission-critical uptime.
This article explores how satellite evolved from a peripheral technology into an indispensable strategic asset, the operational and architectural challenges facing modern service providers, and what the future holds as the industry hurtles toward deeper integration with 5G, cloud computing, and AI architectures.
Detailed Chronology: The Evolution of Satellite in Modern Telecom
To understand how satellite earned its seat at the primary telecommunications table, it is necessary to examine the technological and operational milestones that reshaped the industry over the past several years.
The Era of Isolation: Pre-2020s
Prior to the widespread commercialization of LEO constellations, the satellite sector was dominated by Geostationary Earth Orbit (GEO) satellites. While GEO satellites provided vast coverage areas, their extreme distance from Earth (roughly 35,786 kilometers) introduced high latency, making real-time applications, cloud computing, and voice-over-IP (VoIP) challenging. During this era, satellite deployments were typically siloed. Enterprises used them strictly for remote backhaul where laying fiber was financially or geographically impossible. Telcos largely viewed satellite as a distinct, disconnected business line rather than an integrated component of their core service portfolios.
The LEO Disruption and Hybrid Integration (2020–2024)
The launch and commercial scaling of LEO satellite constellations revolutionized the performance baseline of space-based communications. Operating at altitudes between 160 and 2,000 kilometers, LEO satellites dramatically reduced latency to terrestrial-comparable levels while offering exponentially higher throughput.
During this period, early adopters began testing hybrid network models. Telecommunications operators realized that relying entirely on terrestrial fiber or microwave links left enterprises vulnerable to localized disruptions, natural disasters, and physical cut lines. Managed service providers like Marlink began stepping into the breach, bridging the gap between legacy satellite operators and mainstream service providers. What began as isolated enterprise trials slowly transitioned into structured proof-of-concepts.
The Mainstream Tipping Point (2025–2026)
Over the past 12 to 18 months, the industry has crossed a definitive Rubicon. Satellite has transitioned from isolated trials into large-scale production environments supporting thousands of enterprise locations globally. Service providers are no longer treating satellite as an afterthought; instead, it is actively baked into their core product strategies.
As Olivier Gommes noted, market awareness has skyrocketed. Enterprise customers are no longer asking if they should use satellite, but how they can integrate multi-orbit satellite solutions into broader hybrid architectures alongside 4G/5G, subsea cables, and cloud platforms.
Supporting Context & Metrics: Shifting Customer Demands
The transformation of satellite infrastructure is fundamentally driven by a structural evolution in customer expectations. According to industry insights heading into Capacity Europe 2026, enterprise requirements have pivoted across three core pillars: Resilience, Application Performance, and Security.
[Traditional Telecom Architecture]
   ├── Terrestrial Fiber-Optic Lines (Primary)
   └── Standard Cellular Backhaul (Secondary)
        └── *Vulnerable to regional cuts, natural disasters, and latency bottlenecks.*

[Modern Hybrid Telecom Architecture (Marlink Model)]
   ├── Terrestrial Core (Fiber / 5G)
   ├── LEO Satellite Constellations (Low Latency / High Throughput)
   └── GEO/MEO Backups (Wide Coverage / Redundancy)
        └── *Unified under a single managed service provider with zero operational friction.*
1. The Demand for Unprecedented Resilience
In an era where digital downtime can cost enterprises millions of dollars per hour, network failure is not an option. Recent vulnerabilities in global subsea cable infrastructure have underscored the fragility of relying exclusively on terrestrial routes. Enterprises are demanding diverse, independent connectivity paths. Satellite provides an infallible alternative route that bypasses terrestrial bottlenecks entirely, ensuring continuous business operations during regional outages or physical infrastructure damage.
2. Rapid Site Deployment and Edge Expansion
Traditional terrestrial provisioning can take weeks or months as providers negotiate right-of-way permissions, trench fiber, and install physical routing hardware. For energy companies, construction sites, retail pop-ups, and emergency response teams, this timeline is untenable. Satellite terminals—particularly compact, high-performance LEO hardware—can be drop-shipped to a location and activated within hours, extending enterprise networks to the exact edge of operations.
3. Interdependence in the Digital Ecosystem
Connectivity no longer exists in a vacuum. Modern enterprises operate within complex, cloud-native environments that integrate artificial intelligence, IoT sensors, heavy data analytics, and decentralized IT infrastructure. Gommes emphasizes that decisions made regarding network connectivity directly impact cloud performance and cybersecurity postures. Consequently, enterprises are moving away from piecemeal vendor management in favor of holistic, integrated solutions.
Official Statements and Industry Insights
In his pre-event briefing for Capacity Europe, Olivier Gommes, CP of Technology and Innovation at Marlink, offered deep technical and strategic insights into the current state of the telecommunications market.

Addressing the changing expectations of telecommunications operators, Gommes stated:
"For telcos, satellite has become something customers increasingly expect to see as part of a connectivity portfolio. Enterprise customers are asking about resilience, back-up connectivity, rapid site deployment and extending connectivity into locations where terrestrial services aren’t always practical."
Despite the clear benefits, Gommes pointed out a major operational hurdle for mainstream operators: the sheer administrative and logistical overhead of managing multiple satellite networks.
"Service providers are also reluctant to manage the overhead of every satellite, operator, technology roadmap, and certification process. Nor do they want to deal with the model support. Providers are looking for a simpler way to bring the services to market, making room for companies like Marlink to sit in the middle."
By operating as an agnostic managed service provider, Marlink abstracts away the underlying technical complexities—negotiating across different constellations, orbits, and service models—to deliver a unified, turnkey service to telcos and enterprise clients.
On the trap of oversimplification, Gommes warned providers against falling into the "connectivity weeds":
"A service like Starlink can appear very straightforward initially, but enterprise-scale deployments quickly introduce additional requirements around billing, logistics, network integration, security, installation, support, and service management."
Finally, reflecting on the broader macroeconomic and structural benefits of satellite integration, Gommes highlighted its role in safeguarding global infrastructure:
"We’ll continue to see strong uptake for enterprise connectivity, particularly where resilience and rapid deployment are important. Just as importantly, satellite will play a growing role in protecting network infrastructure and supporting business continuity strategies. Ongoing conversations surrounding subsea cable resilience have demonstrated the need for diverse, independent connectivity paths. Satellite provides that option."
Future Outlook: The Next Horizon for Satellite and Digital Infrastructure
As the telecommunications industry converges in London for Capacity Europe 2026 (October 13–15), the dialogue surrounding digital infrastructure is shifting from coexistence to total convergence.
1. Multi-Orbit Orchestration and Software-Defined Networking (SD-WAN)
The future of satellite is multi-orbit. Rather than choosing between LEO, MEO, and GEO, next-generation enterprise networks will utilize intelligent, software-defined orchestration layers. These systems will dynamically route traffic across terrestrial 5G, fiber, and various satellite constellations in real-time, optimizing for cost, latency, and bandwidth depending on application demands.
2. Deep Integration with 5G and Direct-to-Device (D2D) Technologies
The boundary between cellular and satellite networks is rapidly blurring. Standards-based 3GPP non-terrestrial networks (NTN) are paving the way for seamless roaming between cellular towers and orbiting satellites. This convergence will enable ubiquitous IoT tracking, emergency messaging, and continuous enterprise connectivity without requiring specialized, bulky terminals.
3. Economic Opportunities for Telcos
For telecommunications operators, satellite is no longer a peripheral cost center; it is a vital commercial growth engine. As the digital revolution accelerates and enterprises demand uncompromising reliability across every square kilometer of the globe, telcos that successfully integrate satellite into their core portfolios will capture higher enterprise market share, secure superior retention rates, and future-proof their network architectures against unforeseen disruptions.
Olivier Gommes will elaborate further on these themes during his participation in the Snapshot Presentations: Key developments shaping Europe’s digital infrastructure panel at Capacity Europe 2026.
Join an estimated 4,000 industry leaders, executives, and decision-makers in London from October 13–15, 2026, to connect across the entire digital infrastructure spectrum—including fiber, data centers, cloud, and AI architecture. Register for Capacity Europe to secure your place at the forefront of the connectivity revolution.