By Catie Owen | Regional Content & Insights Lead
Published: October 14, 2026
Executive Overview
For the better part of the decade, the global technology narrative has been utterly dominated by software. Tech giants, venture capitalists, and sovereign states have locked horns in an unyielding arms race, obsessing over parameter counts, algorithmic efficiency, and the relentless quest for ever-smarter artificial intelligence models. Every few months, a new foundational model has emerged, promising to reshape industries, redefine human productivity, and alter the geopolitical balance.
However, as the artificial intelligence revolution matures from a speculative gold rush into an engine of the global economy, a profound realization is taking hold among industry leaders: the true bottleneck—and the ultimate battleground—is no longer being fought in the lines of code.
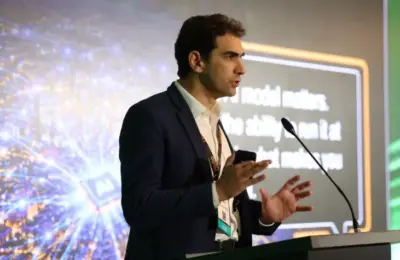
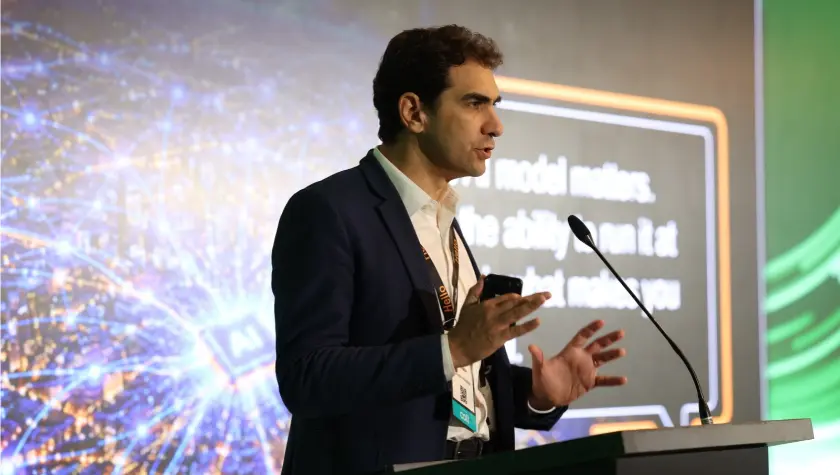
Opening the second day of the landmark 25th-anniversary edition of Capacity Europe, Michael Trabbia, CEO of Orange Wholesale, delivered a paradigm-shifting message that cut straight through the software hype. “The AI models matter,” Trabbia told Capacity following his opening keynote. “But what really matters is the ability to use it at scale.”
That capability does not materialize from thin air. It relies entirely on heavy, physical infrastructure: next-generation data centres, high-density fibre-optic networks, robust energy grids, and transcontinental subsea cable systems. In short, the underlying ecosystem dictates how data moves, where compute lives, and how AI becomes deeply embedded across economies and societies.
As global spending on data centres hurtles past the USD $800 billion mark this year—and projects toward well over a trillion dollars in the near future—connectivity has ceased to be treated as a background utility. It has been elevated to a strategic, highly sovereign national asset.
Detailed Chronology: The Shift from Algorithms to Assets
The transition from software supremacy to infrastructure dominance has been accelerated by the sheer velocity of enterprise AI deployment. To understand how the telecommunications and digital infrastructure markets arrived at this juncture, one must examine the shifting priorities of the past several years.
Phase One: The Software and Compute Sprints (2022–2024)
In the immediate wake of the generative AI boom, attention was hyper-focused on foundational models and the silicon required to train them. Enterprises scrambled to secure specialized graphics processing units (GPUs) and Tensor Processing Units (TPUs). Cloud service providers built massive, localized clusters to accommodate the staggering computational demands of large language models (LLMs). During this era, infrastructure was viewed merely as a reactive vessel—something to be spun up quickly to catch the wave of algorithmic breakthroughs.
Phase Two: The Bottleneck Crisis and the Petabit Era (2025)
As AI deployments moved out of sandbox environments and into mission-critical, enterprise-wide workflows, the limitations of legacy networks became painfully apparent. Organizations quickly realized that training a model in one location was useless if the resulting intelligence could not be transmitted across continents securely, instantly, and without latency.
This realization ushered in what Trabbia appropriately terms "the petabit era." Telecommunications operators found themselves forced to rethink backbone networks, moving away from conventional fibre pair leasing toward massive, dedicated cable systems designed explicitly for hyperscale and AI workloads.
Phase Three: The Sovereignty and Physical Convergence (2026)
At Capacity Europe 2026, the convergence of AI demand and physical infrastructure reached a definitive crescendo. No longer content with viewing digital sovereignty through the lens of data localization laws and software regulations, European policymakers and industry titans recognized that control of physical assets—subsea cables, domestic fibre rings, and sovereign data centres—is the absolute prerequisite for digital independence.
The announcement of major pan-European infrastructure projects during the conference underscored this new reality: the race for AI supremacy is, fundamentally, a race to build the physical world beneath it.
Supporting Context & Metrics: The Scale of the Infrastructure Boom
The numbers driving the modern connectivity landscape are staggering, reflecting an industry undergoing a generational transformation.
- Global Data Centre Spending: According to industry insights highlighted by Orange Wholesale, global investments in data centres have already surpassed USD $800 billion in 2026 alone, with projections showing expenditures scaling to over USD $1 trillion annually in the coming years.
- The Time-to-Market Mismatch: While new AI models and software iterations appear every few months, the physical infrastructure required to support them operates on an entirely different geological timeline. Data centre developments typically take five to seven years from initial conception to full operational capacity. Similarly, new fibre routes and subsea backbone networks require extensive, multi-year planning and deployment cycles. This structural mismatch has made long-term strategic anticipation non-negotiable.
- Orange’s Aggressive Footprint: To meet this soaring demand, telecom operators are committing to massive capital expenditures. Orange has laid out a roadmap to deploy 2.5 million kilometres of fibre by 2028. Simultaneously, the company has partnered with infrastructure investor Morrison to develop 400MW of advanced data centre capacity in France.
This profound disparity between the rapid-fire evolution of software and the deliberate, long-term nature of civil engineering has created a brand-new hierarchy of economic and strategic value.

Official Statements and Industry Perspectives
The sentiment echoing across the corridors of Capacity Europe was unified: those who control the physical conduits of the digital economy hold the keys to the future.
Michael Trabbia on the Real Battleground
Refocusing the industry’s attention away from silicon and toward steel and glass, Michael Trabbia emphasized that infrastructure ownership is now a matter of economic survival:
"The AI models matter, but what really matters is the ability to use it at scale… This acceleration is huge. And when you invest that kind of money, you need to be sure of your connectivity."
Confronting Geopolitical Vulnerabilities and the "Kill Switch" Risk
Trabbia was equally vocal about the geopolitical dimensions of infrastructure ownership, warning businesses and governments alike of the inherent risks of depending on foreign-controlled transit routes and platforms:
"You cannot talk about sovereignty without talking about physical infrastructure. The first dimension is to be in control of the infrastructure where your data, your services, your AI, and digital services will be running… There is this risk for every company of what people call the ‘kill switch,’ meaning that a service could be switched off by a foreign government for any geopolitical reason. Because of this, sovereignty is not just an option — it’s a necessity."
Trabbia’s sobering assessment encapsulates a growing consensus across Europe: "If you don’t control your infrastructure, you don’t control anything."
Building the AI Highways: The Pisces Subsea Project
To combat these vulnerabilities, European operators are actively forging new pathways. A prime example brought to light at Capacity Europe is the formalization of the Pisces subsea cable system.
Developed through a joint venture between Orange, Equitix, and MDM—and bolstered by crucial financial backing from the European Union’s Connecting Europe Facility (CEF)—the approximately 3,125-kilometre Pisces system will connect Ireland, France, Spain, and Portugal using 16 advanced fibre pairs.
Ireland has rapidly evolved into one of Europe’s most vital cloud and data-centre hubs. By directly linking Ireland to continental Europe while bypassing legacy transit routes through the UK, the Pisces project delivers the route diversity, low latency, and high-capacity resilience required to support modern hyperscale and AI workloads.
Future Outlook: The Ecosystem Imperative
As the artificial intelligence market continues its relentless maturation, the winners of the next decade will not necessarily be the companies that write the cleverest algorithms. Rather, they will be the entities that successfully engineer, fund, and protect the physical foundations required to keep those models operating at scale.
For Europe, this moment represents a historic dual challenge and opportunity. The continent boasts mature telecommunications operators, extensive legacy fibre assets, and expanding connectivity hubs. However, maintaining true competitiveness in the AI era requires a fundamental shift in mindset: moving from reactive utility management to proactive, continent-scale infrastructure planning.
As Trabbia asserted during his keynote, the immense volume and cost of the infrastructure required to support Europe’s digital ambitions mean that no single operator, private investor, or government can tackle the challenge in isolation.
The future demands an ecosystem perspective. By forging robust, cross-border public-private partnerships—exemplified by initiatives like the Pisces cable and the Morrison data centre joint venture—the telecommunications sector is laying down the digital highways of tomorrow.
Ultimately, the message emerging from Capacity Europe 2026 is unambiguous: the race to shape the artificial intelligence era is, at its core, a race to build the physical world beneath it.