Executive Overview
The landscape of modern insurtech is undergoing a radical structural shift, driven by the convergence of vertical software-as-a-service (SaaS) and artificial intelligence. Slingshot Insurance, an AI-native embedded insurance platform, has officially emerged from stealth mode, announcing a massive $27 million seed funding round. Co-led by institutional investor Rally Ventures and specialty insurance leader Skyward Group, the round also saw participation from prominent industry veterans—including insurance heavyweight Jim Hays, who will secure a coveted seat on Slingshot’s board of directors.
In an industry traditionally dominated by antiquated systems, manual paperwork, and fragmented communication loops, Slingshot aims to streamline the mechanics of low-ticket, high-volume micro-insurance. By deploying proprietary AI models to automate data sharing, underwriting coordination, and administrative compliance, the Minneapolis-based startup bridges the chasm between legacy insurance carriers and modern digital marketplaces.
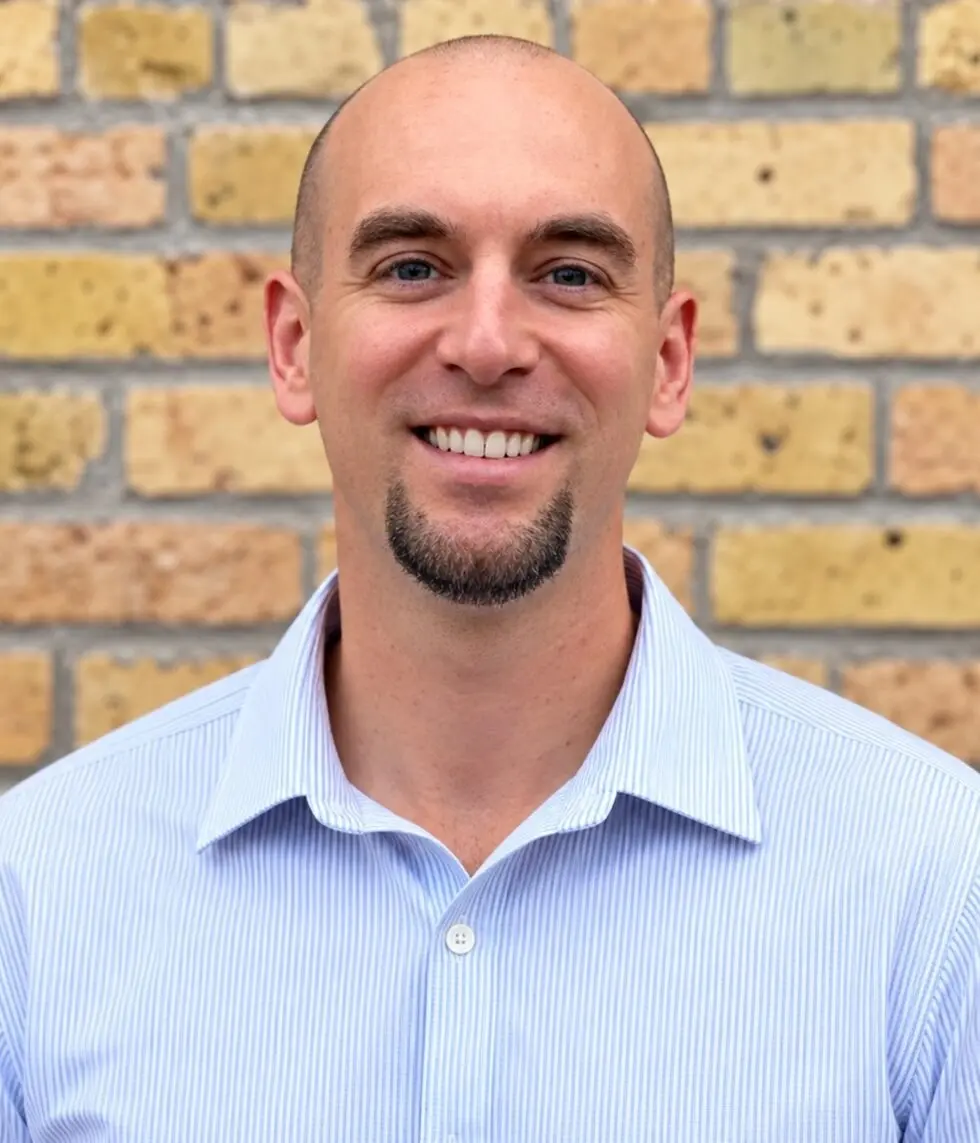
Led by first-time founder and CEO Ethan Genteman—formerly the chief actuarial officer at publicly traded Palomar Holdings—Slingshot officially commenced operations on July 1. Armed with a lean six-person team, the company has already secured its first major design partner and customer, Vertical Insure, which services over 750,000 policyholders. Beyond its core technology-provider revenue model, Slingshot is executing an aggressive M&A strategy to acquire a licensed carrier, positioning the startup to handle both the software infrastructure and the financial balance-sheet backing under one unified roof.
Detailed Chronology: From Basement Prototypes to a $27M Launch
The genesis of Slingshot Insurance traces back to a convergence of technical frustration, macroeconomic shifts in vertical SaaS, and a seasoned actuary seeking to eradicate systemic inefficiencies in specialty insurance.
The Spark of Innovation
Roughly a year ago, Ethan Genteman found himself wrestling with a fundamental problem in the property-and-casualty market: why were micro-policies—such as a $25 flight cancellation or youth sports injury waiver—so economically unviable to administer? Traditional insurers relied on human-intensive spreadsheets, disconnected legacy databases, and sluggish approval workflows that crippled the profit margins of low-premium transactions.
Working out of his basement, Genteman began coding and architecting prototypes designed to automate the heavy lifting of insurance data ingestion and compliance checking. As an actuary who had previously scaled the data and actuarial infrastructure at Palomar Holdings—expanding the firm far beyond its earthquake insurance roots—Genteman possessed a unique vantage point on where technology could compress operational expenditure.
The Rally Ventures Partnership
By late 2025, Genteman’s vision caught the attention of Rally Ventures, a venture capital firm with a distinct strategy: identifying unmet market needs and systematically co-founding portfolio companies to address them. Rally had already co-founded Vertical Insure, a specialized embedded insurance provider led by CEO Brock Noland. Vertical Insure was experiencing explosive demand from platforms seeking to offer insurance at checkout, but was routinely bottlenecked by the agonizingly slow approval processes of incumbent carriers.
Recognizing a prime synergy, Rally leaned into its co-creation playbook. The firm collaborated with Genteman to formalize Slingshot as an enterprise designed explicitly to solve the infrastructure and regulatory bottlenecks plaguing vertical SaaS and embedded distribution channels.
Stepping Out of Stealth
On July 1, 2025, Slingshot formally transitioned from stealth operations. Securing $27 million in seed capital in the current macroeconomic climate underscores institutional conviction in the embedded insurance thesis. With backing from Rally Ventures, Skyward Group, and veterans like Jim Hays, the startup is poised to rapidly deploy its platform. Genteman officially departed his post at Palomar Holdings to helm Slingshot full-time, setting the stage for the launch of its inaugural commercial program this month.
Supporting Context & Metrics: Making the Economics of a $25 Policy Work
To understand Slingshot’s value proposition, one must examine the brutal unit economics of micro-insurance.
The Micro-Policy Margin Crisis
Consider a typical consumer transaction: a parent registers a child for a local youth sports league, spending $2,000 on a competitive volleyball season. At checkout, the platform offers a $25 rider policy covering unexpected season cancellation or sports injuries.
To the consumer, the utility is obvious. But to the insurer and the distributor, the transactional math is punishing. Every policy requires regulatory filings, policy administration, ongoing reporting, and potential claims processing. When an average premium sits at $25, administrative overhead quickly outpaces top-line revenue.
In a hypothetical scenario outlined by Genteman, a program collecting $500,000 in gross written premiums with a standard 10% operating margin generates a meager $50,000 in actual profit. For legacy insurance carriers burdened by manual compliance checks and administrative bloat, that margin is completely unviable. Consequently, millions of dollars in potential revenue are left on the table.
The Vertical SaaS Opportunity
Simultaneously, vertical SaaS companies—software platforms tailored to hyper-specific industries like pet care, property rentals, childcare, and sports leagues—are actively seeking new monetization avenues beyond traditional subscription seat fees. These software providers are uniquely positioned to offer contextual insurance because they already sit at the center of the consumer transaction.
- Childcare Platforms: A babysitting marketplace can instantly bundle backup care insurance, indemnifying parents if a sitter cancels at the eleventh hour.
- Pet Boarding Software: Veterinary and boarding platforms can embed unexpected medical expense riders directly into kennel reservation checkouts.
- Equipment Rentals: Industrial or consumer tool rental applications can provide instantaneous damage and theft protection.
However, despite possessing the distribution channel and customer intent, SaaS operators lack the licensing, regulatory compliance frameworks, and insurance relationships required to bring these products to market. Slingshot steps in as the operational bridge, transforming an abstract insurance product concept into a fully compliant, automated reality.
The Technological Architecture
Slingshot replaces the web of legacy emails, manual CSV spreadsheets, and disparate databases with an intelligent, API-driven orchestration layer.
- AI-Driven Data Ingestion: The platform leverages artificial intelligence to parse, process, and synchronize massive volumes of transactional data between policy distributors and backend insurance carriers.
- Auditable Decision Trails: While automation handles the repetitive administrative burden, Slingshot maintains transparent, immutable audit logs, ensuring that human underwriters and compliance officers can review, verify, and override decisions as needed.
- Transparent Pricing Model: Slingshot levies a straightforward 5% technology fee to administer programs through its software layer.
Crucially, Slingshot’s M&A roadmap points toward acquiring a licensed insurance carrier. This vertical integration will allow the startup to provide both the software stack and the balance-sheet capital required to underwrite risks natively, bypassing the sluggish authorization cycles of traditional carriers entirely.
Official Statements and Industry Perspectives
The launch of Slingshot has drawn praise from prominent figures across the insurtech and venture capital ecosystems, validating the pressing need for infrastructure reform in embedded insurance.
Ethan Genteman, Co-Founder and CEO of Slingshot Insurance:
"We’re not a carrier yet, but we are rapidly closing on our carrier… The challenge is that the insurance and regulatory landscape is incredibly complex, and most SaaS companies don’t have the expertise, industry relationships or understanding of where to begin. Insurance becomes another product that can be offered naturally within the existing customer experience."
Brock Noland, Co-Founder of Slingshot and CEO of Vertical Insure:
"We can design the products our customers need almost overnight, but the industry is highly regulated, and we need delegated authority just to write and distribute what we’ve built. The antiquated approval process on the carrier-side slows everything down."
Justin Kaufenberg, Managing Director at Rally Ventures:
"That experience [running SportsEngine] gave me firsthand insight into the opportunity for software companies to generate revenue through embedded financial products… To get the carrier, the reinsurance, the underwriting platform, the data flow engine, the reporting capabilities, the claims handling, the embedded distribution engine, and every other part of the offering from a single vendor is unheard of."
Future Outlook & Strategic Roadmap
As Slingshot exits stealth with $27 million in fresh capital, the startup’s immediate trajectory focuses on three core pillars: execution, scaling design partnerships, and completing its carrier acquisition.
1. Launching Inaugural Programs
With Vertical Insure acting as its primary design partner—servicing upwards of 750,000 users—Slingshot’s first live programs are rolling out this month. The success and velocity of these initial deployments will serve as a proof-of-concept for broader market expansion.
2. Expanding the SaaS Ecosystem
Slingshot’s go-to-market strategy hinges on convincing vertical SaaS executives that embedded insurance is an untapped engine for gross margin expansion. By abstracting away the regulatory friction, licensing hurdles, and technical integrations, Slingshot lowers the barrier to entry so drastically that launching an insurance line item becomes as simple as installing a software plugin.
3. Achieving Full Balance-Sheet Integration
While currently operating as a technology provider charging a 5% administrative fee, Slingshot’s imminent acquisition of a licensed carrier represents its ultimate strategic moat. By controlling both the software infrastructure and the risk-bearing balance sheet, Slingshot will eliminate reliance on third-party capacity providers, enabling unprecedented speed-to-market for bespoke micro-insurance products.
In an industry long resistant to disruption, Slingshot Insurance’s blend of actuarial rigor, AI-native engineering, and venture-backed momentum signals that the era of friction-free embedded insurance has officially arrived.