Executive Overview
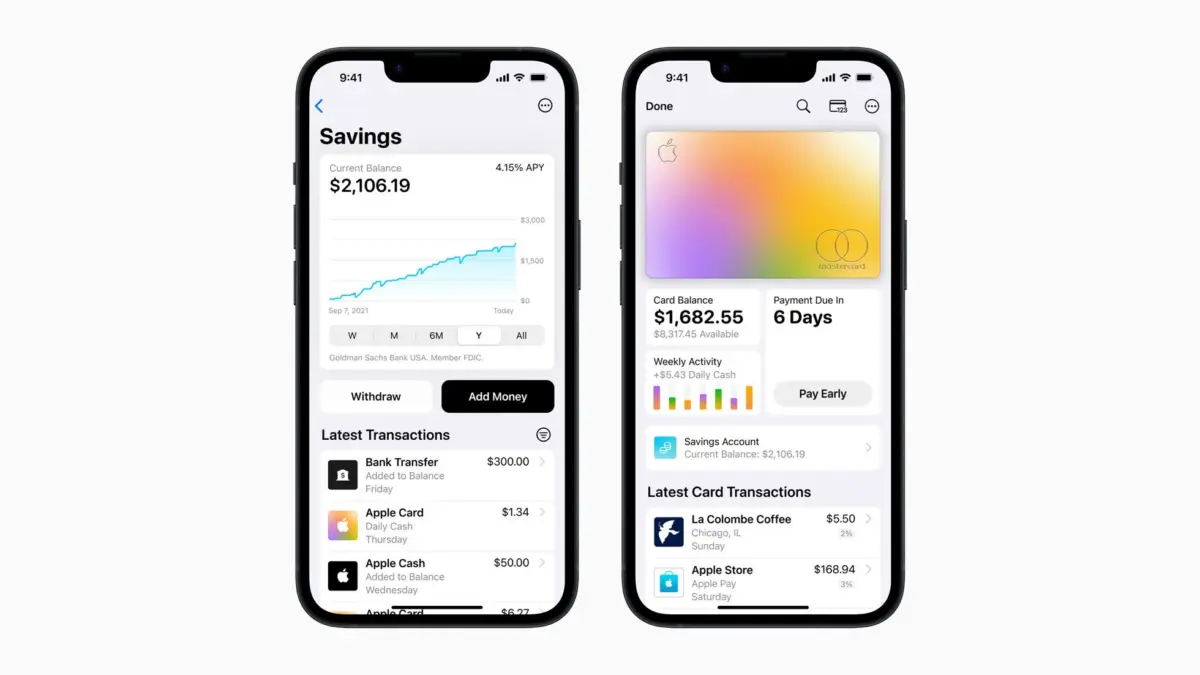
In a strategic maneuver that further blurs the traditional boundaries between Silicon Valley and Wall Street, Apple—in partnership with banking titan Goldman Sachs—officially launched a high-yield savings account tailored exclusively for Apple Card holders. Announced on a Monday that marked yet another milestone in the consumer technology sector, the feature allows users to deposit their "Daily Cash" rewards directly into a digital vault boasting an impressive Annual Percentage Yield (APY) of 4.15%.
To put this figure into perspective, the national average for traditional savings accounts hovers well below 0.50%, while legacy brick-and-mortar institutions like Bank of America offer a meager 0.01% APY on standard consumer savings. By offering a yield that dwarfs traditional retail banking options, Apple is not merely rewarding its loyal customer base; it is aggressively capturing consumer capital. Beyond automatic Daily Cash deposits, users can fund the account directly from external bank accounts up to a maximum balance of $250,000, fully insured by the Federal Deposit Insurance Corporation (FDIC) via Goldman Sachs.
This launch is far from an isolated financial experiment. It represents the latest salvo in Apple’s calculated, multi-year push into personal finance—a sector the company views as both a retention mechanism for its massive hardware ecosystem and a lucrative new revenue stream. Coming on the heels of the rollout of Apple’s "Buy Now, Pay Later" (BNPL) service, which directly challenges fintech giants like Klarna and Affirm, the savings account solidifies Apple’s transformation into a formidable neo-banking alternative.
This report provides an exhaustive analysis of the new Apple Card savings feature, examining its mechanics, competitive landscape, strategic implications, and what this means for the future of consumer banking.
Detailed Chronology: The Evolution of Apple Financial Services
To fully understand the significance of the 4.15% APY savings account, one must trace the deliberate, methodical evolution of Apple’s financial services portfolio over the past decade.
The Foundation: Apple Pay (2014)
Apple’s journey into the financial sector began quietly in October 2014 with the launch of Apple Pay. Initially met with skepticism from traditional merchants and card issuers, Apple Pay laid the groundwork for contactless payments. By digitizing the credit card experience and embedding biometric security (Touch ID and Face ID) into the transaction flow, Apple established user trust regarding financial data on mobile devices.
The Hardware-Adjacent Credit Card: Apple Card (2019)
In March 2019, Apple announced the Apple Card, developed in collaboration with Goldman Sachs and backed by the Mastercard network. Launched later that year, the card broke industry conventions by offering a sleek, laser-etched titanium physical card with no numbers on it, coupled with a robust digital experience housed entirely within the iOS Wallet app. Crucially, the card introduced "Daily Cash"—a cashback reward system that paid users instantly upon transaction settlement, rather than waiting for the end of a billing cycle. Users earned 1% on standard purchases, 2% when using Apple Pay, and 3% on purchases made with select merchants, including Apple itself, Uber, Walgreens, and Nike.
Expanding the Credit Ecosystem: Apple Pay Later (Early 2023)
As consumer demand for flexible payment solutions surged, Apple introduced its "Buy Now, Pay Later" (BNPL) service, aptly named Apple Pay Later. Integrated seamlessly into the Wallet app, this feature allowed qualified users to split purchases ranging from $50 to $1,000 into four equal payments spread over six weeks, entirely free of interest and hidden fees. This rollout directly pitted Apple against established BNPL juggernauts like Klarna, Affirm, and Block’s Afterpay, leveraging Apple’s unmatched integration within the iOS ecosystem to capture checkout traffic.
The Savings Account Debut (April 2023)
The natural evolution of accumulating Daily Cash rewards was finding a place for them to grow. On April 17, 2023, Apple and Goldman Sachs bridged the gap between spending and saving by introducing the high-yield savings account. By allowing users to route their Daily Cash directly into a compound-interest-bearing account—and supplement those rewards with external bank deposits—Apple effectively created a closed-loop financial ecosystem where money could be earned, spent, saved, and managed without ever downloading a traditional banking app.
Supporting Context & Metrics: How Apple Stacks Up Against Traditional Banking
The headline-grabbing figure of a 4.15% APY immediately drew comparisons to both traditional banking behemoths and agile online-only neo-banks. To evaluate the true value proposition of Apple’s offering, financial analysts have looked closely at the prevailing macroeconomic climate, the competitive landscape, and user mechanics.
Macroeconomic Tailwinds
The launch of Apple’s savings account coincided with a period of elevated federal interest rates. As the U.S. Federal Reserve steadily hiked benchmark rates to combat inflation, traditional banks lagged far behind in passing those yields on to everyday depositors. While commercial banks continued to hoard cheap deposits at 0.01% to 0.05% APY, online banks and digital wealth platforms began offering yields north of 4%. Apple entered this high-rate environment at precisely the right psychological moment, offering consumers a frictionless way to escape low-yielding legacy accounts.
Comparative Analysis: APY Rates Across the Industry
| Institution / Product | Annual Percentage Yield (APY) | Account Type | Minimum Balance / Fees |
|---|---|---|---|
| Apple / Goldman Sachs Savings | 4.15% | High-Yield Savings | $0 minimum / $0 fees |
| Bank of America (Standard Savings) | 0.01% | Traditional Savings | Monthly maintenance fees apply unless conditions are met |
| Chase Bank (Savings) | 0.01% | Traditional Savings | Monthly maintenance fees apply unless conditions are met |
| Marcus by Goldman Sachs | Competitive Online Rates | High-Yield Savings | $0 minimum / $0 fees |
| Ally Bank | Competitive Online Rates | High-Yield Savings | $0 minimum / $0 fees |
While Apple’s 4.15% APY was highly competitive at launch, financial watchdogs were quick to note that it is not technically the absolute highest rate available on the open market. Specialized online neo-banks and credit unions occasionally offer yields surpassing 5% depending on economic conditions. Furthermore, Apple explicitly noted in its terms that the 4.15% APY is variable and subject to change at any time based on market conditions.
Mechanics and Limitations
Despite the attractive yield, the Apple Savings account comes with distinct structural parameters:
- Ecosystem Lock-In: To open and manage the account, users must have an Apple Card, an iPhone running the latest version of iOS, and a two-factor authentication setup associated with their Apple ID. Android users and non-Apple Card holders need not apply.
- Deposit Limits: Through its partnership with Goldman Sachs, deposits are protected up to the standard FDIC insurance limit of $250,000. However, cumulative deposit limits apply to individual accounts.
- Funding Sources: Users can deposit funds automatically via Daily Cash rewards, or manually via linked external bank accounts or Apple Cash balances.
Official Statements and Industry Perspective
The strategic intent behind the high-yield savings account was articulated clearly by Apple’s leadership team during the product rollout.
"Our goal is to build tools that help users lead healthier financial lives, and building Savings into Apple Card in Wallet enables them to spend, send, and save Daily Cash directly and seamlessly — all from one place," said Jennifer Bailey, Apple’s vice president of Apple Pay and Apple Wallet, in an official corporate statement.
This emphasis on "financial health" is a core tenet of Apple’s marketing narrative. By designing tools that discourage debt accumulation (such as transparent interest calculators for the Apple Card) and encourage automated wealth accumulation through Daily Cash compounding, Apple seeks to differentiate itself from predatory lending practices historically associated with major credit card issuers.
Industry analysts, however, view the move through a dual lens of consumer utility and aggressive ecosystem fortification. By embedding financial services deep into the native iOS Wallet app, Apple increases the "switching cost" for consumers considering moving from an iPhone to an Android device. If a user’s daily spending rewards, BNPL installment loans, and high-yield savings are all managed effortlessly within iOS, the friction of leaving the Apple ecosystem multiplies exponentially.
Goldman Sachs, meanwhile, views the partnership as a vital customer acquisition channel. While Goldman has faced well-publicized operational challenges and strategic pivots regarding its broader consumer banking ambitions (such as scaling back its Marcus brand operations), its white-label partnership with Apple grants the investment bank access to tens of millions of affluent, tech-savvy consumers without the immense customer acquisition costs typically borne by digital banks.
Future Outlook: Where is Apple’s Financial Empire Headed?
As the dust settles on the initial rollout of the high-yield savings account, financial technologists and Wall Street observers are already speculating on Apple’s next moves. The company’s methodical, deliberate expansion into personal finance suggests that a comprehensive suite of banking products may eventually emerge.
1. Wealth Management and Investment Products
With hundreds of billions of dollars potentially flowing into savings accounts backed by Goldman Sachs, the natural next step for Apple is wealth management. Could "Apple Wealth" be on the horizon? Analysts suggest that offering automated micro-investing, fractional share trading, or retirement planning tools (such as automated IRAs) within the Wallet app would be a logical extension of its current financial framework. By partnering with established brokerages or expanding its partnership with Goldman Sachs, Apple could easily transition from a savings repository to a primary hub for consumer investments.
2. International Expansion
Currently, the Apple Card, Apple Pay Later, and the high-yield savings account are restricted almost exclusively to the United States. Regulatory hurdles, varying interchange fee caps, and complex regional banking compliance laws have slowed international deployments. However, as Apple refines its compliance infrastructure in the U.S., pressure will mount from international consumers—particularly in lucrative markets like Europe and Asia—to bring these financial perks abroad. Overcoming regulatory roadblocks across different jurisdictions will be the primary bottleneck for international growth.
3. The Super-App Ambition
In many ways, Apple is quietly constructing the Western equivalent of an Asian "super-app" like WeChat or Alipay. While Western consumers have historically preferred specialized, single-purpose apps for banking, shopping, and communication, Apple is centralizing these functions inside the iOS operating system and the Wallet application. By unifying payments (Apple Pay), credit (Apple Card), short-term financing (Apple Pay Later), and high-yield savings under a single, highly secure umbrella, Apple is positioning itself not just as a consumer electronics manufacturer, but as an indispensable financial utility in the daily lives of billions of people.
Conclusion
Apple’s introduction of a high-yield savings account offering 4.15% APY is much more than a routine product update—it is a masterclass in ecosystem synergy. By pairing industry-leading software design with compelling financial incentives, Apple and Goldman Sachs have created a frictionless banking tool that appeals to both casual spenders and savvy savers alike. As Apple continues to chip away at the traditional banking sector, legacy institutions ignore the tech giant’s financial ambitions at their own peril. The wallet in your pocket is no longer just holding your credit cards; it is rapidly becoming your primary bank.