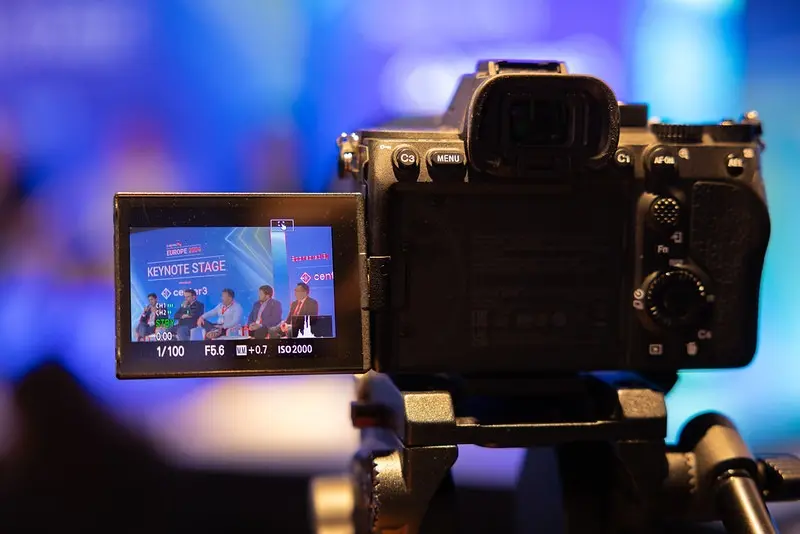
LONDON — As the global digital infrastructure sector gathers at the InterContinental London, The O2, for the landmark 25th anniversary edition of Capacity Europe, the mood across the industry is a complex cocktail of hyper-growth ambition and sobering operational reality. Running from October 13 to 15—with pre-event activities kicking off on October 12—the conference is set to welcome more than 4,000 decision-makers representing the vanguard of fibre, data centres, cloud, and artificial intelligence (AI) infrastructure.
However, this milestone anniversary arrives at a moment of unprecedented strain. While hyperscalers and telecommunications titans race to capture the generational gold rush of AI deployment, foundational bottlenecks are threatening to derail the roadmap. From looming power shortages and aggressive local opposition to soaring debt structures and the rising geopolitical vulnerabilities of subsea networks, the industry is transitioning from a period of unbridled expansion to an era of intense, risk-mitigating scrutiny.
Across three dedicated stages and a series of specialized summits, five critical questions will define the discourse in London, setting the agenda for the future of global digital connectivity.
Executive Overview: Navigating the New Operational Paradigm
The digital infrastructure landscape of late 2026 bears little resemblance to the hyper-abundant environment of previous years. The meteoric rise of generative AI and autonomous AI agents has completely transformed network dynamics, shifting the primary driver of web activity from human consumption to machine-to-machine transactions. This evolution has forced a profound re-evaluation of network capacity, architectural layouts, and capital allocation.
Yet, as operators scramble to scale, they are running headfirst into systemic friction:
- Energy Constraints: Power availability is no longer just a utility concern; it is the ultimate bottleneck for data centre deployment.
- Regulatory & Community Backlash: Environmental pushback and zoning disputes are delaying tens of billions of dollars in vital infrastructure across both sides of the Atlantic.
- The Capital Squeeze: Lenders and investors are adopting a much more conservative posture, treating delivery delays and regulatory gridlock as formal credit risks.
- Geopolitical Vulnerability: Subsea cable networks are increasingly viewed as critical national security assets, drawing heightened scrutiny from military alliances like NATO.
This convergence of challenges forms the backdrop for Capacity Europe 2026, where industry leaders must confront whether the current pace of innovation can be sustained without structural reform.
Detailed Chronology & Key Thematic Pillars
The 2026 agenda is structured around several high-stakes debates, dissecting the operational, financial, and geopolitical hurdles facing the ecosystem.
1. Monetizing the AI Boom: Revenue vs. Traffic
The opening sessions on the Market Forces stage dive straight into the monetization paradox. While AI workloads are generating unprecedented volumes of network traffic, telecom operators and infrastructure providers are grappling with how to translate this boom into sustainable, high-margin revenue streams.
In the opening keynote, Colt CEO Keri Gilder will examine the paradigm shift of machine-generated network activity. This will be followed by a high-powered executive panel featuring Orange Wholesale International CEO Valerie Cussac, STC’s Mohammed Al-Abbadi, T Wholesale’s Dimitrios Rizoulis, Vodafone’s Fanan Henriques, and Sparkle CEO Enrico Bagnasco. Together, they will tackle the hard truths of turning AI ambition into actual balance-sheet returns, navigating boardroom capex priorities, and operating within tightening regulatory frameworks.
Later in the day, leaders from AWS and NVIDIA will take the stage for the session "Beyond Infrastructure: Who Really Monetises AI?", debating where true value resides in the service stack and which business models enterprise customers are actually willing to fund. For carriers, the ultimate question remains: will the AI revolution expand operating margins, or will it simply flood pipes with unmonetized traffic?
2. The Infrastructure Backlash: Navigating the Build Crisis
The United States has served as a cautionary tale for the data centre sector. In the second quarter of 2026 alone, local opposition successfully blocked 45 data centre projects with an estimated combined value of $68 billion. Notably, in Texas, Governor Greg Abbott ordered the state’s environmental regulator to halt the issuance of new data centre permits pending a comprehensive grid audit by ERCOT. BloombergNEF estimates this administrative pause places nearly 50GW of proposed capacity—representing close to a fifth of the entire US pipeline—at immediate risk.
Europe faces a parallel crisis, albeit manifested through different institutional channels. According to Capacity’s tracking of European data centre resistance, more than $42 billion of proposed regional projects have been delayed, significantly reworked, or outright cancelled due to public concern over water usage and power draw. In Scotland, for instance, government ministers have instituted mandatory reviews for every data centre application exceeding 50MW.
To address these hurdles, the AI Build stage will host targeted sessions such as "From Grid Constraint to Competitive Growth"—featuring National Grid’s David Adkins and Verne CEO Dominic Ward—and "Licence to Operate", which gathers executives from Telehouse, Ark Datacentres, Khazna, and Greenscale to explore proactive community engagement and streamlined approval processes.

3. Wiring the Future: Europe’s Looming Fibre Bottleneck
The explosive growth of AI is fundamentally altering continental and international connectivity requirements. The keynote panel "Wiring the AI Boom"—featuring euNetworks CEO Marisa Trisolino, EXA Infrastructure CEO Jim Fagan, Retelit CEO Jorge Alvarez, and Verizon President Jeff Hulse—will focus on the urgent need for fast-tracked corridor builds and dark fibre strategies.
This sense of urgency is well-founded. Industry analysts and executives, including Colt’s Joe Scattareggia, have repeatedly warned of an impending transatlantic capacity crunch, estimating that European networks have a very narrow window to upgrade core infrastructure before demand completely outstrips supply.
Simultaneously, the market is undergoing aggressive consolidation. Deutsche Telekom’s agreement to acquire Polish broadband provider INEA and its wholesale sister company Fiberhost for approximately €1 billion underscores the race for scale. This trend will be dissected further in sessions like "Scaling or Selling"—featuring Nexfibre CEO Rajiv Datta and CVC DIF’s Simon Rosas—alongside a Financial Times-chaired panel re-evaluating the valuation of European fibre assets.
4. Securing the Depths: Subsea Cables as Critical Assets
Subsea security has evolved rapidly from a niche technical concern into a boardroom-level priority. Recent geopolitical tensions have placed submarine infrastructure under intense scrutiny. Reuters reported that NATO allies successfully disrupted a coordinated Russian subsea sabotage plot, following a troubling series of at least 11 cable incidents in the Baltic Sea between late 2023 and the end of last year. In response, the European Commission launched a €347 million subsea infrastructure initiative alongside a comprehensive Cable Security Toolbox.
The newly introduced Global Critical Infrastructure Summit will open with insights from Laurie Walker, head of NATO’s Critical Undersea Infrastructure Coordination Cell. Furthermore, the Market Forces stage session "Chokepoints & Shockwaves"—featuring representatives from Meta, SEACOM, and Midgard Infra—will address the physical vulnerabilities of international links and debate whether hyperscalers or sovereign operators should bear ultimate responsibility for protecting critical subsea routes.
This ownership debate has gained fresh momentum with Meta’s announcement of Petal, a landmark 7,000km subsea cable spanning from France to the US. Set to deliver unprecedented petabit-scale capacity across the Atlantic by 2029, with Orange supporting the French landing site, the project highlights the shifting balance of power in international connectivity.
5. Financial Prudence and Capital Market Caution
Beneath the technological optimism lies a more cautious, risk-averse financial community. Just weeks before the conference, the sector received a stark reminder of the execution risks plaguing mega-scale AI investments. Oracle issued a force majeure notice to the developer of Project Jupiter—its massive 2.45GW Stargate campus in New Mexico—allowing the tech giant to defer payments if the site misses its scheduled 2028 operational target. The delay stems from a nearly six-month slippage in the construction of the gas pipeline intended to power the facility, driven by repeated permit denials.
Lenders are increasingly factoring local opposition and administrative delays into formal credit risk assessments. At the same time, high-profile neocloud players like CoreWeave, whose total debt burden reached $35 billion by the end of June, highlight the pressures of heavy leverage in a shifting interest rate environment.
To unpack these dynamics, the AI Build stage will feature discussions on funding models, followed by "Capital at Risk" with Kao Data CEO David Bloom, DigitalBridge’s Zach Gellman, and executives from Guggenheim, BGO Data Centers, and Echelon. Additionally, the Digital Infrastructure Finance & Investment Summit will bring together Fitch Ratings Chief Economist Brian Coulton alongside representatives from Macquarie, the Qatar Investment Authority, and Ares Management to evaluate structural mismatches, such as aligning 20-year project debt with 10-year data centre lease contracts.
Future Outlook: What Lies Ahead for Digital Infrastructure
As Capacity Europe 2026 unfolds at the InterContinental London, the overarching consensus is clear: the digital infrastructure sector has entered its maturity phase. The period of easy capital and frictionless deployment has given way to a disciplined operating environment where execution, community relations, power procurement, and risk management dictate success.
Over the coming days, delegates will not only debate these complex challenges but will also forge the strategic partnerships required to navigate them. For an industry underwriting the backbone of the global digital economy, the outcomes of these discussions in London will shape the trajectory of connectivity, cloud adoption, and AI deployment for the remainder of the decade.
Capacity will be reporting live from London throughout the event. Standard conference registration rates apply, with late booking fees taking effect following the close of early-access windows.