London, October 7, 2026 — As the telecommunications industry prepares for the milestone 25th anniversary edition of Capacity Europe in London, the strategic conversation surrounding digital infrastructure is undergoing a fundamental shift. For years, the narrative of fibre deployment, capital investment, and technological innovation has been dominated by major metropolitan hubs. However, rising demand, demographic shifts, and the explosive growth of artificial intelligence (AI) and deep-tech startups are drawing the industry’s gaze outward.
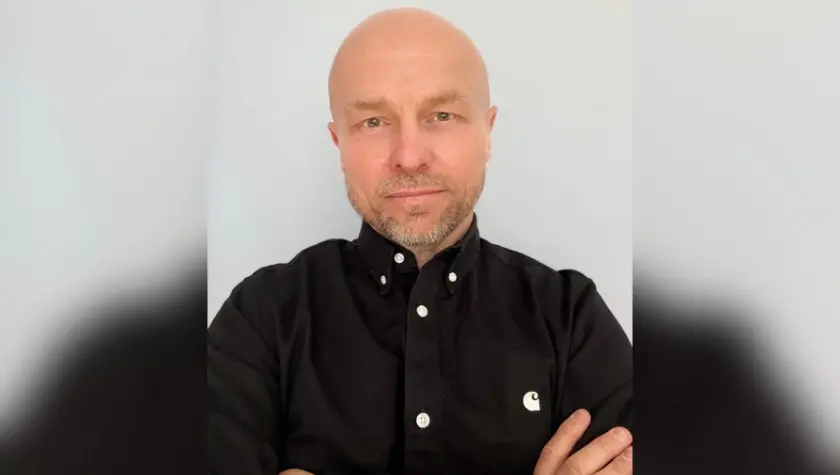
Ahead of his appearance at the upcoming industry summit, Matt Partridge, Managing Director of Enterprise and Wholesale at LightSpeed Networks, sat down with Capacity to discuss how secondary market strategies have evolved. In a landscape where traditional urban overbuild gives way to dynamic, high-growth regional corridors, operators are being forced to rethink their business models, abandon combative competitive tactics, and reposition fibre not just as a commodity asset, but as an agile, service-driven technology platform.
Executive Overview
The economic geography of the United Kingdom is changing. Historically, telecommunications investors poured capital into densely populated Tier 1 metropolitan areas, treating secondary and rural markets as low-priority margins of the digital grid. Today, that calculus is obsolete.
Driven by decentralization—where jobs increasingly move to where people want to live—secondary markets are rapidly maturing into what industry leaders now term "Tier 1.5" markets. These regions combine the lower overbuild saturation of rural areas with the high-octane data demands of AI startups, agritech innovators, and advanced research clusters.
However, capitalizing on this unique landscape requires a departure from traditional playbook strategies. According to LightSpeed Networks, companies operating in these secondary zones must move beyond simple fibre economics. They must transition from residential broadband providers into enterprise-grade platforms defined by three core tenets: security, observability, and agility.
As Partridge and other industry experts prepare to debate these themes on the panel “Banking Fibre Beyond Tier One: What Actually Works?” at Capacity Europe 2026, the imperative for the sector is clear: long-term success in secondary markets demands a holistic, ecosystem-driven approach that prioritizes customer experience and economic gravity over raw geographic density.
Detailed Chronology: The Evolution of Secondary Market Strategy
To understand how the secondary market narrative reached its current inflection point, it is necessary to examine the evolutionary trajectory of fibre deployment over the past decade.
Phase 1: The Urban Gold Rush (Mid-2010s to Early 2020s)
In the early days of the UK’s full-fibre rollout, independent altnets (alternative network providers) and legacy carriers alike targeted high-density urban areas. The primary metric of success was homes passed per square kilometre. High-density postcodes offered quick wins for user acquisition, leading to aggressive overbuild in major cities. However, this hyper-focus eventually triggered fierce price competition, compressing margins and causing bandwidth prices to continually decline.
Phase 2: Saturation and the Pivot to Regions (2022–2024)
As metropolitan areas grew saturated and overbuilt, returns on investment in Tier 1 cities began to diminish. Simultaneously, post-pandemic migration patterns shifted populations toward suburban, semi-rural, and regional corridors. Workers relocated seeking better quality of life, prompting tech-focused enterprises, research facilities, and advanced manufacturing hubs to follow suit. Operators began venturing outside traditional boundaries, discovering that secondary markets possessed surprising economic vitality.
Phase 3: The Rise of Tier 1.5 and Platform Integration (2025–Present)
By 2026, the distinction between rural backwaters and urban powerhouses has blurred. Regional clusters—typified by the Oxford-Cambridge (OxCam) corridor—have emerged as hotbeds for innovation, housing everything from cutting-edge AI labs to automated agricultural operations. LightSpeed Networks and similar forward-thinking operators have recognized that these regions cannot be treated with a one-size-fits-all rural strategy. Instead, the focus has shifted toward building integrated digital platforms that leverage "outside-in" thinking, focusing heavily on what the customer needs rather than merely laying plastic and glass in the ground.
Supporting Context & Metrics: The Anatomy of a Modern Growth Corridor
The viability of secondary markets hinges on a complex blend of demographics, industrial diversification, and evolving enterprise needs.
The Paradox of Secondary Geography
Operating in parts of the UK that have largely escaped the fierce overbuild seen in major cities presents a distinct market dynamic. As Matt Partridge notes, this landscape is not necessarily "easier" to operate in, but it is fundamentally different.
[Traditional Tier 1 Markets]
- High population density & overbuild
- Commodity-driven pricing wars
- Service quality erosion & high churn

[Emerging "Tier 1.5" Corridors]
- Diverse enterprise mix (AI, Agritech, Life Sciences)
- Collaborative regional ecosystems
- Focus on security, observability, & platform agility
Despite lower residential density in certain pockets, these regions rank among the nation’s fastest-growing and most data-hungry economic zones. The secret lies in industrial diversity. Within a single footprint, an AI startup in Cambridge might operate just miles away from an agricultural enterprise deploying massive IoT sensor arrays. This blend of advanced digital requirements creates a unique commercial profile that traditional urban centers rarely replicate.
The Dangers of the Price-War Trap
A persistent challenge in modern telecommunications is the relentless race to the bottom on pricing. Bandwidth remains one of the few technological commodities that consistently gets cheaper over time. When regional and national providers aggressively undercut one another to win market share, the financial deficit has to be absorbed somewhere.
In many cases, it is the service and support experience that suffers. This creates a self-sabotaging cycle:
- Providers drop prices to secure rapid customer acquisition.
- Operational budgets for customer support and network maintenance are trimmed.
- End-users experience sub-par service quality and inadequate technical support.
- Frustrated customers switch providers every few years, perpetuating industry-wide churn.
To break this cycle, forward-thinking operators are realizing that service quality, robust security, and end-to-end network observability are far more important to enterprise buyers than marginal cost savings.
Official Statements and Industry Insights
Speaking candidly about the shifting paradigms of digital infrastructure, Matt Partridge emphasized that financial success in secondary markets requires looking beyond simple postcode analytics.

"We operate in a part of the UK that hasn’t seen the same level of overbuild as major metropolitan areas, which gives us a very different market dynamic. That’s not to say it’s easier; it’s just a largely different landscape from urban areas," said Matt Partridge, Managing Director of Enterprise and Wholesale at LightSpeed Networks.
Addressing the eclectic mix of businesses inhabiting these regional zones, Partridge highlighted the convergence of traditional and cutting-edge industries:
"Alongside rural communities, we’re seeing strong growth in AI startups, deep-tech businesses, and agritech innovation… For us, the conversation goes beyond fibre economics. We’re transitioning from a residential fibre provider into a much more enterprise-focused business. We’re evolving how we go to market, how we serve customers, and how we generate revenue from the same underlying asset."
Partridge also underscored the psychological and cultural barriers that continue to plague the telecommunications sector, particularly the historic reluctance of large operators to collaborate:
"Large operators are often conditioned to compete for 100% of the revenue opportunity instead of collaborating to create better outcomes for customers. Yet many of the fastest-growing regional economies thrive because businesses work together, particularly during growth phases… We talk a lot about collaboration as an industry, but customers don’t always see enough evidence of it. Shifting towards a more ecosystem-driven approach could unlock far more value in these growth markets."
Moving from theoretical collaboration to practical deployment, Partridge explained LightSpeed’s consultative methodology regarding growth corridors like the OxCam arc:
"It’s about understanding customers’ perspective and industrial development. Despite research, manufacturing, logistics, life sciences, energy, and technology businesses all having different requirements, they often develop within the same growth corridors. It’s about following those economic growth patterns rather than just counting addresses on a map."
Future Outlook: Fibre as a Platform
As the telecommunications sector looks toward the next decade, the very definition of a successful fibre enterprise is undergoing a radical reimagining. Industry leaders predict that the next generation of market winners may not even describe themselves primarily as "fibre businesses."
The Platform Paradigm Shift
Just as cloud computing providers manage massive server farms without branding themselves as mere hardware warehouses, future infrastructure leaders will position themselves as comprehensive digital platforms. Fibre will remain the indispensable underlying physical asset, but it will function as part of a broader, value-added technology stack.
These forward-looking businesses will enable flexible consumption models—driven by usage analytics and automation—allowing them to step entirely out of the mundane physical infrastructure debate and focus squarely on the transformative business outcomes they enable for enterprise clients.
The Three Pillars of Modern Strategy
To successfully execute this transition, LightSpeed Networks has operationalized a strict set of foundational principles driven by "outside-in" thinking. According to Partridge, every strategic initiative, product development, and cultural shift within the organization must align with three non-negotiable pillars:
- Security: Ensuring enterprise-grade data protection and resilient network architecture from the ground up.
- Observability: Providing clients with deep, transparent visibility into their network performance and bandwidth usage.
- Agility: Maintaining the operational flexibility to adapt rapidly to the changing demands of AI, deep-tech, and high-growth enterprise customers.
If any potential product, corporate decision, or strategic investment fails to contribute positively to one or more of these pillars, the organization re-evaluates its necessity. This uncompromising focus serves as a compass for navigating the complexities of modern connectivity.
Join the Conversation at Capacity Europe 2026
The dialogue surrounding secondary market bankability, Tier 1.5 regional corridors, and the future of platform-driven infrastructure will take center stage at the upcoming Capacity Europe 2026 conference in London, running from October 13 to October 15, 2026.
Marking its historic 25th anniversary, the event is projected to convene over 3,500 to 4,000 global decision-makers, industry pioneers, and investors spanning the entire digital ecosystem—including fibre operators, data centre developers, cloud architects, and AI infrastructure leaders.
Matt Partridge will bring these insights directly to the stage as a featured speaker on the panel session titled: “Banking Fibre Beyond Tier One: What Actually Works?”
For infrastructure investors, altnet operators, and enterprise customers looking to understand where the puck is moving in European digital connectivity, Capacity Europe offers an unmissable forum for networking, debate, and strategic alignment.
To register for the event and connect with leaders shaping the future of fibre, cloud, and AI infrastructure, visit the official Capacity Europe Registration Portal.