Date: 16 October 2026
Estimated Reading Time: 9 minutes
Executive Overview
Europe’s digital infrastructure ecosystem is caught in a profound paradox. On the surface, the macro-environment has rarely looked healthier: demand for data center capacity is surging to unprecedented heights, driven by the relentless expansion of cloud computing and artificial intelligence (AI), and institutional capital is abundant, eager to fund viable projects. Yet, industry leaders are sounding the alarm. The central bottleneck throttling Europe’s digital ambitions is no longer a lack of customers or capital; it is the sheer, compounding difficulty of delivering predictable megawatts on a reliable timeline.
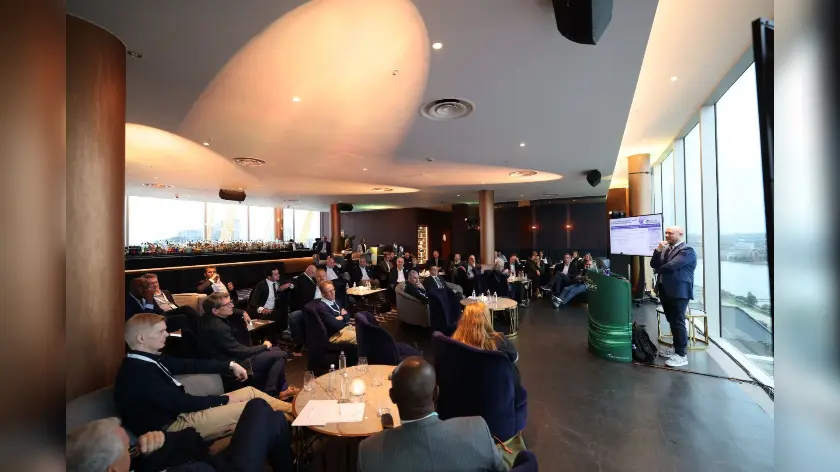
On October 12, 2026, just ahead of the flagship Capacity Europe conference in London, roughly 30 senior executives—comprising data centre operators, connectivity providers, hyperscale anchor tenants, infrastructure lenders, legal experts, and network owners—gathered behind closed doors for the Digital Infra Leaders roundtable. Held under the Chatham House Rule, the session confronted two pivotal questions: What transforms a geographic location into bankable, scalable capacity, and can the notoriously ad-hoc process of digital hub creation be industrialized and made repeatable?
The consensus emerging from the roundtable was stark. Power availability, regulatory permitting, grid access, and community consent have completely eclipsed traditional site-selection metrics. Certainty of delivery has become the ultimate currency. As one frustrated participant bluntly remarked, "If we were allowed to spend the trillion dollars, we would love to." Instead, developers find themselves stalled by bureaucratic red tape, oversubscribed grid queues, and a rising tide of local opposition.
Detailed Chronology: The Road to the London Roundtable
The urgency surrounding the October 12 roundtable did not materialize in a vacuum; it is the culmination of years of structural strain across Europe’s power and planning systems.
The Escalating Grid Crisis (2024–2025)
For years, the European digital economy expanded on the assumption that power infrastructure would scale organically alongside digital demand. However, the exponential rise of high-density AI workloads fundamentally shattered this assumption. By late 2024 and mid-2025, national grid operators across the continent began sounding alarms over unprecedented connection queues.
In the United Kingdom, the situation reached a tipping point when the national demand connections queue swelled from 41 gigawatts (GW) in November 2024 to a staggering 125 GW by June 2025, with data centre applications alone accounting for approximately 73 GW. Recognizing that speculative applications—many submitted by developers or battery-storage operations with little capital or genuine intent to build—were choking the pipeline, energy regulator Ofgem intervened. On July 16, 2025, Ofgem opened a high-stakes consultation proposing strict commitment fees and rigorous progress milestones to clear speculative projects. This consultation closed on September 16, 2025, setting the stage for a broader reckoning across Europe regarding how grid capacity is allocated.
The October 12, 2026 Roundtable
Against this backdrop of regulatory tightening and soaring demand, the London roundtable convened on October 12, 2026. The closed-door discussions immediately stripped away industry optimism to focus on operational realities. Polling data gathered during the session revealed alarming metrics:
- 70% of attendees stated they expect securing a standard grid connection to take longer than 18 months.
- 74% of participants identified community acceptance as a critical strategic risk to future operations.
- When asked to grade the industry’s current effectiveness in handling local community relations and public narrative, attendees gave a dismal average score of 4 out of 10.
These stark figures anchored the day’s debates, driving home the reality that technical and financial viability are meaningless without regulatory and social license to operate.
Supporting Context & Metrics: The Anatomy of a Constrained Market
The discussions in London illuminated several deep-seated structural friction points that continue to define the European digital infrastructure landscape.
1. Certainty as the Ultimate Currency
When polled on what makes a location truly durable and attractive for long-term investment, 81% of attendees pointed directly to deliverable megawatts backed by clear amortization milestones, followed closely by streamlined permitting frameworks and competitive power pricing.
End-user hyperscalers have fundamentally altered their site-selection methodologies. Rather than negotiating based on speculative master plans, customers now work aggressively backward from a fixed Ready-for-Service (RFS) date. They meticulously audit every prerequisite—securing power allocations, land acquisition, and on-site construction contracting. If any single element lags behind schedule, the hyperscale customer simply walks away to an alternative site.
For institutional lenders, this operational rigidity has altered risk assessments. Project finance committees now treat the end-user customer as the mandatory starting point of any infrastructure evaluation. Without a stable, investment-grade offtaker and a robust, perfectly matched contract structure, financing conversations do not even begin. Furthermore, because a high volume of projects now feature strong investment-grade counterparties, competition for capital is cutthroat. Commercial banks are prioritizing pristine balance sheets, while fixed-income instruments are assuming a larger role—though invariably encumbered by stringent utilization restrictions.
2. The Geographic Shift: Moving East and South
The pressures facing established markets are forcing a radical redesign of Europe’s infrastructure map. 84% of roundtable attendees predicted that future growth will inevitably burst beyond the traditional FLAP-D markets (Frankfurt, London, Amsterdam, Paris, and Dublin).
While older network topologies were structured purely around human population centers, the next generation of infrastructure must follow the availability of raw inputs: power, water, land, and renewable energy generation. Nevertheless, because AI inference workloads require low latency, these new corridors are still tethered to population centers, driving unprecedented interest in secondary and tertiary markets.
Participants summarized the new geographic paradigm in three words: "East and South." Among the emerging hubs highlighted during the sessions were:

- Warsaw, Poland: Benefiting from supportive regional economic policies and available industrial land.
- Madrid and Broader Spain: Capitalizing on abundant solar power generation and favorable municipal attitudes.
- Norway: Offering vast reserves of low-cost, green hydroelectric power.
- Second- and Third-Tier German Cities: Absorbing overflow demand as Frankfurt faces severe grid constraints.
- Turkey: Emerging as a strategic wildcard due to its unique geographic bridging position between Europe and Asia.
Paris remained a subject of sharp division. While some delegates lauded its nuclear-backed, low-carbon baseload energy profile, others with direct development experience characterized it as an exceptionally hostile market plagued by municipal-level resistance. Meanwhile, established metros are regionalizing, with new developments pushing up to 50 kilometers away from central business districts, while Amsterdam and Dublin remain heavily restricted by permitting bottlenecks.
3. The Speculative Queue and Supply Chain Gridlock
The UK and continental markets alike continue to battle the fallout of speculative queuing. Because grid operators have historically been legally obligated to treat every connection application equally, speculative data centre and battery storage applications have choked transmission queues.
This bureaucratic logjam creates a hidden secondary crisis: supply chain and engineering constraints. When transmission queues are artificially bloated with ghost projects, equipment manufacturers, specialized engineers, and construction contractors are spread dangerously thin. This systemic dilution delays viable, fully funded projects that are ready to break ground immediately.
Compounding this is the labyrinthine nature of cross-border permitting. While a data centre facility must navigate a single municipal authority, international subsea cables and cross-border fiber routes require approvals from dozens of separate jurisdictions, many of which share little economic incentive to expedite the project. Consequently, developers are increasingly exploring "behind-the-meter" power solutions or rushing to secure sites with pre-existing grid allocations.
4. Losing the Narrative: The Community Relations Crisis
Perhaps the most alarming consensus to emerge from the roundtable was the industry’s collective failure in public relations. With 74% of leaders classifying community resistance as a strategic risk—and 70% predicting it will dictate future investment decisions—the current score of 4 out of 10 for community engagement reflects an existential blind spot.
Public opposition is typically fueled by anxiety over electricity consumption, water usage, perceived lack of local economic dividends, and poor corporate communication. Roundtable participants noted that many of these fears stem from profound public misconceptions—particularly regarding closed-loop water consumption and the potential repurposing of waste heat.
Historically accustomed to operating under strict commercial confidentiality, the data centre industry has found itself unequipped for the intense public scrutiny of the AI era. As one operator warned, if the industry fails to proactively educate the public, that communicative vacuum "will be filled with negative sentiments," leading cautious local mayors to reject projects out of fear of electoral backlash.
Official Statements and Industry Perspectives
Throughout the Chatham House Rule discussions, industry leaders offered candid assessments of the systemic reforms required to keep Europe’s digital economy moving forward:
-
On Power and Deliverability:
- "If we were allowed to spend the trillion dollars, we would love to. Delivering megawatts on a predictable date is the problem." — Anonymous Roundtable Participant
-
On Customer Expectations:
- "They just need certainty. End-users work backwards from the ready-for-service date. If power and land aren’t locked down, they move to the next site." — Data Centre Operator
-
On Market Dynamics and Resilience:
- "There’s no single market that is likely to win. A sudden shift in regulation or grid policy can completely reshape a national market within six months." — Senior Infrastructure Executive
-
On Policy and Advocacy:
- "Large telecoms groups lobby Brussels with dedicated teams, but the wider digital infrastructure sector has rarely spoken with one voice on what it needs. We need to move from the back seat to the front." — Connectivity Provider Delegate
Future Outlook: Navigating the Road Ahead
As the digital infrastructure community absorbs the insights from the London roundtable and transitions into the 25th anniversary edition of Capacity Europe, the path forward requires a fundamental shift in strategy.
To overcome the power paradox, the industry must transition from passive builders to assertive policy advocates. Participants proposed several critical structural remedies:
- Unified National Policy Frameworks: Consolidating grid connection processes, environmental permitting, and energy procurement into a single, streamlined national digital policy framework with a "one-stop-shop" approval process for major infrastructure projects.
- Proactive Community Engagement: Institutionalizing early-stage public dialogue, ensuring transparent communication regarding resource consumption, and directly tying project developments to tangible local economic benefits (such as district heating networks powered by data centre waste heat).
- Queue Reform and Strategic Prioritization: Pushing regulators across Europe to implement strict financial commitment fees, rigorous milestone tracking, and formal definitions of "strategic demand" to fast-track viable, fully financed projects and purge speculative applicants from transmission queues.
Ultimately, demand for digital capacity is not slowing down, and global capital remains more than willing to back the right ventures. In a marketplace where the exact time-to-megawatt dictates commercial survival, achieving marginal gains in predictability and regulatory alignment will separate the industry winners from those left waiting at the grid’s edge.