Executive Overview
Europe’s artificial intelligence sector is experiencing an unprecedented financial awakening. In the first half of 2026 alone, European AI-focused startups raked in a staggering $23 billion in venture funding—representing a massive 130% surge year-over-year and accounting for more than half (55%) of the continent’s total venture capital deployment. These figures, drawn from a joint report by Crunchbase and the HumanX conference, paint a picture of a vibrant, well-funded ecosystem that is rapidly catching the attention of global investors.
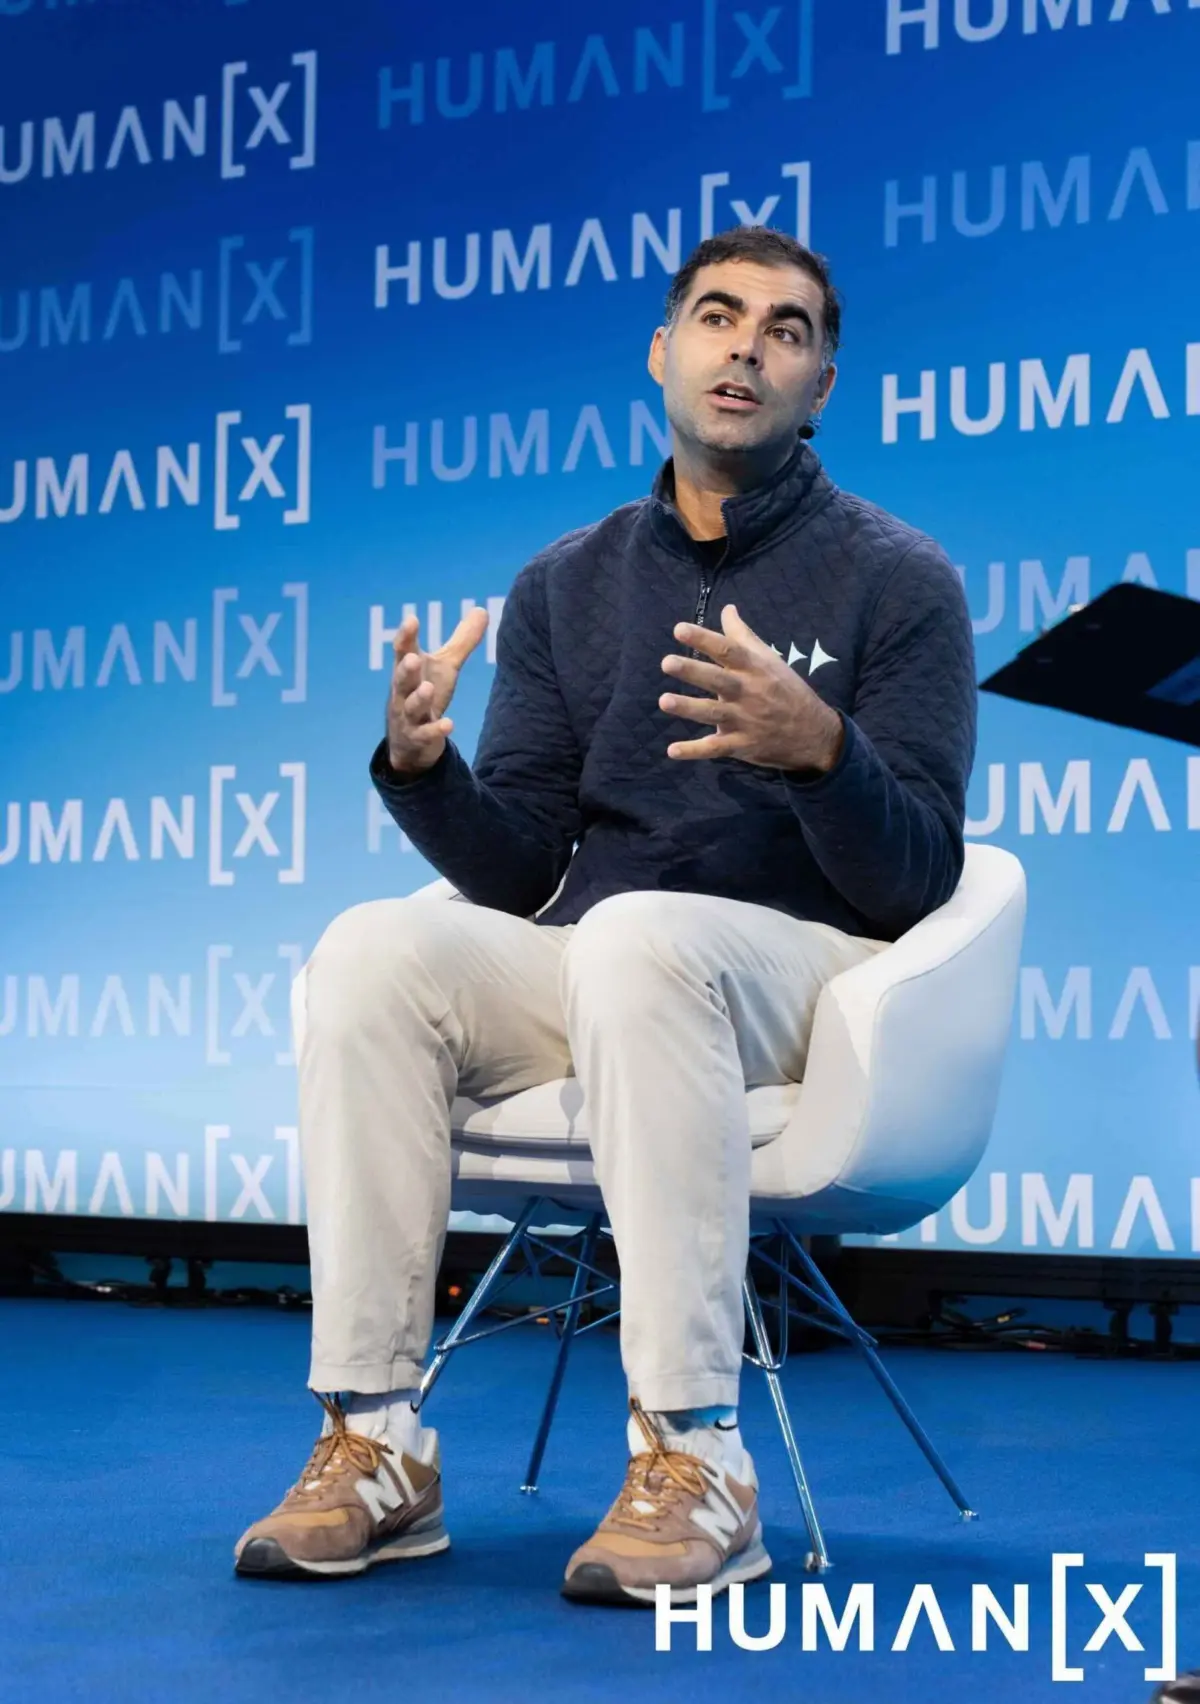
Yet, beneath this golden veneer of record-breaking fundraising lies a persistent structural vulnerability. Funding alone will not guarantee Europe control over its technological destiny. As industry leaders made clear during panel discussions at last month’s HumanX conference in Amsterdam, capital injection is only the first step of a much longer journey. The region’s sovereign AI ambitions are colliding with a glaring market failure: a severe lack of enterprise and government procurement.
While European startups are building world-class technologies, governments and legacy corporations are failing to buy what is being made locally. This missing link—the commercial flywheel of enterprise adoption and public-sector procurement—threatens to relegate Europe to a permanent state of technological dependency. Achieving true AI sovereignty does not require a nation or a trading bloc to own every microscopic layer of the technology stack. Instead, as leaders from companies like Axelera AI and AI71 argue, the path forward demands targeted focus in semiconductors and applications, backed by aggressive institutional purchasing mandates that translate raw financial capital into enduring economic growth.
Detailed Chronology: The Evolution of Europe’s Sovereign AI Landscape
To understand how Europe arrived at this critical juncture in 2026, it is necessary to examine the rapid evolution of the continent’s artificial intelligence strategies over the past several years.
2023–2024: The Awakening and Regulatory Frameworks
Following the generative AI explosion catalyzed by OpenAI’s release of ChatGPT in late 2022, European policymakers were initially caught flat-footed. While the United States dominated foundational model development through massive hyperscaler investments and the United Arab Emirates poured state-backed capital into infrastructure, Europe chose a regulatory route. The drafting and subsequent implementation of the European Union’s landmark Artificial Intelligence Act set global compliance standards but simultaneously stoked fears among local entrepreneurs that over-regulation would stifle innovation.
During this period, European startups struggled to secure the mega-rounds common in Silicon Valley. Most venture capital was funneled into early-stage research, with many of the continent’s brightest engineering talents migrating to American tech giants or setting up operations abroad to access deeper pools of capital and abundant computing power.
2025: The Infrastructure Realization
By 2025, the conversation shifted dramatically from ethics and regulation to sovereignty and infrastructure. European leaders realized that relying entirely on foreign cloud providers, foreign foundational models, and imported microprocessors posed an existential threat to economic security and data privacy.
Governments across the continent began allocating billions of euros to build sovereign cloud infrastructures and support domestic compute initiatives. However, investments remained heavily skewed toward high-risk foundational models—an expensive and ultimately unwinnable race against heavily capitalized U.S. and Chinese tech titans. By late 2025, industry analysts began sounding the alarm: Europe was investing heavily in building AI, but domestic businesses were slow to integrate these home-grown tools into their day-to-day operations.
2026: The Funding Surge and the Procurement Bottleneck
The first half of 2026 brought a historic influx of capital, with European AI startups securing $23 billion. Yet, as experts converged on Amsterdam for the HumanX conference, the narrative shifted from how much money was being raised to where that money was going—and, crucially, who was buying the resulting products.
Discussions at HumanX highlighted a stark contrast between Europe’s funding boom and its sluggish enterprise adoption rates. While startups were successfully closing venture rounds, they faced a risk-averse corporate culture and fragmented public procurement processes. Without domestic buyers, European AI companies found themselves forced to look across the Atlantic for enterprise customers, effectively exporting the economic value generated by European research and capital.
Supporting Context & Metrics: Decoding the Sovereign AI Dilemma
The debate over sovereign AI hinges on a fundamental economic question: Where should governments and investors concentrate their limited resources to capture the technology’s economic value while retaining control over sensitive data?
The "Five-Layer Cake" Framework
To evaluate where Europe should focus, industry leaders frequently reference Nvidia CEO Jensen Huang’s conceptualization of the AI industry as a "five-layer cake":
- Energy: The raw power required to run data centers and compute clusters.
- Chips: The physical semiconductors (GPUs, TPUs, and specialized inference chips) that execute calculations.
- Infrastructure: The cloud platforms, data centers, and networking systems housing the hardware.
- Models: The foundational large language models (LLMs) and neural networks that process data.
- Applications: The user-facing software, enterprise tools, and agentic workflows that deliver practical value to end-users.
Global Disparities in Compute and Energy
Evaluating Europe’s position against global competitors reveals severe structural disadvantages. Europe is a net importer of energy, which drives up the operational costs of running massive data centers. Furthermore, the region lacks the vast concentrations of specialized neural network compute power and frontier research labs found in the United States and parts of Asia.
In sharp contrast, regions like the United Arab Emirates have optimized every layer of the stack. Abu Dhabi boasts the highest per capita compute density in the world, paired with abundant and inexpensive energy resources. This unique advantage has allowed the UAE to implement aggressive national mandates—such as requiring every government agency to integrate agentic AI processes within three months—with the explicit goal of having AI agents handle 50% of all citizen-government interactions over the next two years.
Europe, by contrast, suffers from a fragmented market. While it possesses world-class research talent and a massive unified consumer market of 440 million people, it lacks the cohesive, top-down public procurement strategies that accelerate commercialization in other regions.
Official Statements and Industry Insights
At the HumanX conference in Amsterdam, leading voices in the global AI ecosystem offered sharp critiques and strategic roadmaps for Europe’s future.

Fabrizio Del Maffeo: Focusing on the Semiconductor Layer
Fabrizio Del Maffeo, founder and CEO of Axelera AI—a five-year-old firm specializing in chips for AI inference—argued that Europe does not need to own every single layer of the AI stack to achieve sovereignty. Instead, the continent must carve out strategic niches where it can excel.
"Artificial intelligence will expand from cloud computing, from centralized data centers, to devices closer to us in the physical world," Del Maffeo explained during his onstage session with Crunchbase News. "To enable this, you need specific chips which can run efficiently, at a lower cost, to connect these networks that today are running in the cloud. We are here to solve this problem."
Del Maffeo emphasized that Axelera AI has successfully commercialized two generations of chips for roughly 600 customers and is now expanding into decentralized cloud computing infrastructure. However, he issued a stern warning regarding Europe’s broader economic trajectory:
"What worries me is that we are a little bit lagging behind, and therefore we are missing this value creation, and this will weaken the economies of Europe… We should not be obsessed with controlling the entire stack. In Europe, we have to create value instead of just paying for a service. Creating value means creating a wealthy economy."
He noted that Europe’s cultural resistance to corporate procurement—specifically the hesitation of large, established European enterprises to buy unproven technology from local startups—deprives the ecosystem of the vital growth flywheel seen in the United States.
Mehdi Ghissassi: Prioritizing the Application Layer and Data Sovereignty
Mehdi Ghissassi, chief product and technology officer at Abu Dhabi-based AI71 and a former product leader at Google DeepMind, offered an international perspective on why foundational model dominance is an inefficient target for most regions.
"Competing at the model layer does not make sense," Ghissassi stated, pointing to the immense capital requirements and rapid commodity traps of training frontier models. "There will be two, three, or four companies that can afford to be in the race."
Instead, Ghissassi stressed that the application layer is where true sovereign control and data protection are achieved.

"The application layer is the one that is really important, for sovereignty where you want to own your data. You want to make sure that it stays with you, be it that you’re a government or an enterprise. If you’re giving away your trade secrets and know-how, nobody stops whoever is being a provider to you today, from replacing you."
Highlighting the UAE’s operational velocity, Ghissassi contrasted Abu Dhabi’s proactive approach with Europe’s structural hurdles:
"What helps is the mandate, the pace at which things happen, the availability of compute, both in terms of sovereign clouds, or on-prem, or global clouds, and then the amount of capital that is being invested to help transform these companies to benefit from these technologies."
Future Outlook: Can Europe Bridge the Procurement Gap?
As Europe moves through the second half of 2026, the $23 billion injected into its AI startups serves as both a milestone and a warning. The capital is present, the technical talent is world-class, and the regulatory environment is settling into a predictable rhythm. Yet, financial abundance cannot substitute for commercial traction.
To transform this capital surge into lasting sovereign strength, European stakeholders must execute a coordinated pivot:
- Cultivating Enterprise Procurement: European corporations must reform their risk-averse procurement policies. Venture capital investors must actively pressure portfolio companies to sell locally, creating a closed-loop economic flywheel that recirculates wealth within the continent.
- Strategic Specialization over Stack Monopoly: Rather than attempting to match the multi-billion-dollar training runs of U.S. hyperscalers, European industrial policy should double down on areas of existing strength—such as specialized inference chips (exemplified by Axelera AI), edge computing, industrial automation, and enterprise-specific application layers.
- Government Mandates as Catalysts: Inspired by models in the Middle East and parts of Asia, European governments must leverage public procurement. By mandating the integration of local AI solutions across public administration, healthcare, and education, governments can provide the guaranteed early-stage revenue startups need to scale globally.
Without these foundational shifts in buying behavior, Europe risks financing the technological tools of tomorrow only to watch them—and the economic value they generate—sold to foreign buyers. Sovereign AI is not merely about where data is stored or who builds the base models; it is about who buys, utilizes, and monetizes the intelligence that powers the modern economy.