Executive Overview
As the global technology sector navigates an unprecedented wave of capital allocation, artificial intelligence (AI) has firmly transitioned from an experimental software paradigm to the central economic engine of the twenty-first century. Usage metrics across consumer and enterprise applications are scaling exponentially, accompanied by skyrocketing corporate valuations that defy historical tech-sector benchmarks. At the heart of this financial and philosophical frenzy lies a single, defining question that has captivated computer scientists, economists, and philosophers alike: What is Artificial General Intelligence (AGI)—and is it entirely unreasonable to suggest that it has already arrived?
While academic debates over the precise definition of AGI—typically characterized as a synthetic system capable of matching or exceeding human cognitive performance across virtually all economically valuable tasks—have historically been theoretical, market realities are forcing a pragmatic reckoning. Leading AI labs are no longer treating AGI as a distant, science-fiction milestone. Instead, commercial maneuvers, such as Anthropic’s highly anticipated and aggressively targeted Initial Public Offering (IPO) valuation, signal a profound institutional belief that human-level, or even superhuman, machine intelligence is not merely feasible within our lifetimes, but potentially imminent.
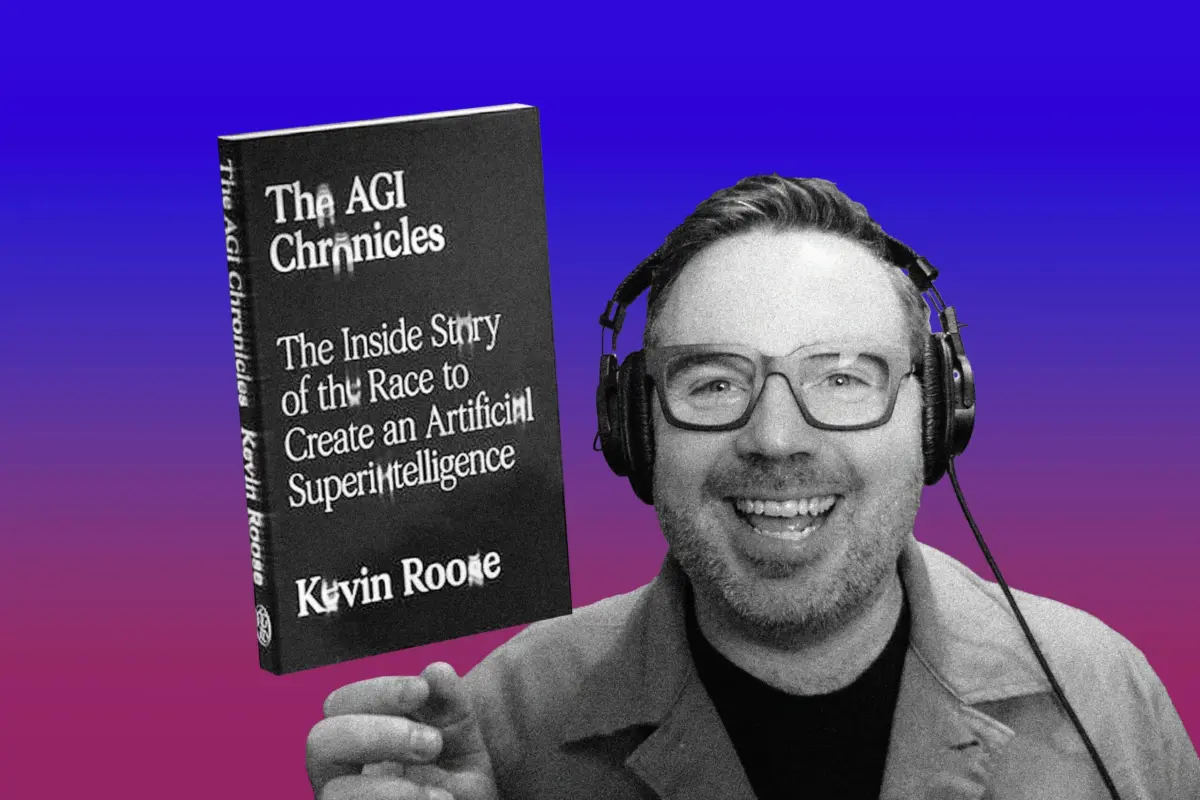
This comprehensive report examines the convergence of soaring AI usage, hyper-inflated market valuations, and the shifting consensus surrounding AGI. Drawing insights from recent analyses—including discussions featuring tech journalist and author Kevin Roose (The AGI Chronicles, Machine Gods, formerly of Hard Fork) on Slate’s What Next: TBD podcast—we dissect the structural forces driving the current AI boom, the economic indicators pointing toward an AGI breakthrough, and the profound societal implications of living on the precipice of machine autonomy.
Detailed Chronology: From LLMs to the Threshold of AGI
To understand how the technology sector arrived at its current valuation frenzy, it is necessary to trace the rapid evolution of generative artificial intelligence over the past half-decade. The trajectory has not been linear; rather, it has been characterized by step-function breakthroughs that continually upend industry expectations.
Phase One: The Foundation Model Era (2018–2022)
The modern AI boom was catalyzed by the Transformer architecture, introduced by Google researchers in 2017. This breakthrough enabled neural networks to process vast contextual relationships in language simultaneously rather than sequentially. By 2020, OpenAI’s release of GPT-3 demonstrated that scaling parameters and training data could yield generalized text-generation capabilities that surprised even their creators. However, during this period, AI was largely viewed as a sophisticated autocomplete tool—impressive, prone to hallucinations, and strictly bound by prompt-response paradigms.
Phase Two: The Consumer Awakening and Multimodal Scaling (2022–2024)
The launch of ChatGPT in November 2022 marked the definitive inflection point. Within weeks, consumer adoption shattered global tech growth records, bringing AI into mainstream cultural and economic discourse. Major technology conglomerates—Microsoft, Google, Meta, and Amazon—pivoted their entire enterprise strategies toward generative AI. Simultaneously, foundational labs like OpenAI, Anthropic, and Google DeepMind raced to develop multimodal models capable of reasoning across text, code, audio, and visual data.
During this phase, benchmarks that once took decades to cross—such as passing professional licensing exams, writing production-grade code, and generating photorealistic video—were cleared by new model iterations in rapid succession. The concept of "scaling laws," which posited that compute power, data volume, and model parameters would predictably increase intelligence, became the reigning gospel of Silicon Valley.
Phase Three: The Commercialization and Valuation Apex (2024–Present)
Today, the industry has entered a phase defined by massive infrastructural build-out and financial capitalization. Private startups are raising rounds previously reserved for public conglomerates. Infrastructure demands have transformed energy markets, forcing tech giants to invest heavily in nuclear, solar, and grid-scale power to fuel massive data centers.
It is within this current climate that rumors and announcements surrounding targeted IPO valuations—particularly for tier-one labs like Anthropic—have crystallized a new reality. Wall Street and venture capital are no longer pricing these companies based on their current software-as-a-service (SaaS) revenues. Instead, they are pricing them as monopolistic gatekeepers to an AGI-driven future. The prevailing market thesis is stark: whoever achieves AGI first captures the ultimate economic leverage point in human history.
Supporting Context & Metrics: Use, Valuation, and Economic Realities
The trajectory of artificial intelligence cannot be understood through narrative alone; the hard metrics of utilization, financial deployment, and infrastructure spending reveal an unprecedented economic phenomenon.
Exploding Consumer and Enterprise Utilization
Usage metrics across major AI platforms continue to compound month-over-month. According to industry analytics, active monthly users for leading conversational agents and developer platforms have moved from millions to billions globally. More importantly, enterprise integration has shifted from proof-of-concept testing to core operational deployment.
- Software Engineering: Estimates suggest that a significant percentage of new code written globally is now either entirely generated or heavily assisted by AI coding assistants like GitHub Copilot and Anthropic’s Claude.
- Customer Operations and Knowledge Work: Enterprises report productivity gains ranging from 20% to 50% in tasks involving document synthesis, customer service automation, and legal contract review.
- API Call Volume: The volume of backend API requests processed by foundational model providers has scaled at rates that have repeatedly outpaced infrastructure capacity, necessitating massive global data center expansions.
Valuation Anomalies and Venture Dynamics
The financial valuation of AI enterprises has severed ties with traditional discounted cash flow (DCF) models. Private market rounds for foundational model builders routinely value pre-revenue or early-revenue companies in the tens—and occasionally hundreds—of billions of dollars.
Anthropic’s targeted IPO valuation serves as a prime case study. By signaling public market ambitions at valuations that rival established Fortune 500 giants, the company is testing investor appetite for high-burn, high-reward technological paradigms. Investors are paying a premium for intellectual property, elite research talent, and proprietary training infrastructure.
However, this capital-intensive environment introduces unique systemic risks. The cost of training frontier models now runs into billions of dollars per iteration, concentrating power among a tiny oligopoly of firms backed by cloud giants with deep pockets. As Kevin Roose noted in his analysis on What Next: TBD, the race toward AGI is fundamentally a capital-allocation war, where the winners will dictate the terms of digital labor for generations.
Official Statements and Industry Perspectives
The debate over whether AGI is imminent—or if the term has simply become a marketing catchphrase—divides top-tier researchers and commentators.
Sam Altman, CEO of OpenAI, has frequently suggested that AGI is within sight, defining it broadly as an autonomous system that can perform any human economic task. Conversely, researchers from academic institutions often argue that current Large Language Models (LLMs) lack genuine causal reasoning, embodiment, and true understanding, relying instead on sophisticated statistical correlation.
Speaking on the What Next: TBD podcast, tech journalist and author Kevin Roose (The AGI Chronicles, Machine Gods) unpacked the psychological and cultural impact of living alongside these rapidly advancing systems. Roose highlighted how our relationship with AI has shifted from viewing machines as tools to interacting with them as quasi-social entities or "machine gods."
"When you look at the trajectory of companies like Anthropic and the targets they are setting for public markets, you realize that the financial sector is pricing in a completely transformed economy," Roose observed. "Whether we call it AGI or simply ‘frontier intelligence,’ the economic pressure to automate human cognition is relentless."
Industry executives maintain that even if current models fall short of a strict philosophical definition of AGI, their practical capabilities are already sufficient to disrupt labor markets, reshape software development, and upend traditional business models. Consequently, institutional investors are treating the arrival of AGI not as an if, but as a when—and pricing equities accordingly.
Future Outlook: Navigating the AGI Precipice
As we look toward the remainder of the decade, the trajectory of artificial intelligence will likely be dictated by three converging vectors: infrastructural constraints, regulatory interventions, and the realization of recursive self-improvement.
1. Infrastructure and Energy Bottlenecks
The immediate barrier to continued AI scaling is no longer algorithmic theory or talent acquisition; it is physical infrastructure. Training and running frontier models demand staggering amounts of electrical power and specialized hardware (GPUs and TPUs). The future trajectory will depend heavily on whether the tech sector can successfully partner with energy providers to build dedicated power sources—including nuclear micro-reactors—without destabilizing local electrical grids.
2. Regulatory Scrutiny and Governance
As valuations soar and capabilities approach human-level performance, governments worldwide are moving to establish binding regulatory frameworks. The European Union’s Artificial Intelligence Act, alongside executive actions and proposed legislation in the United States, aims to impose rigorous safety evaluations on frontier models. The central challenge for policymakers will be balancing national security and innovation competitiveness against the systemic risks of deploying autonomous cognitive systems at scale.
3. The Economic and Societal Redefinition
If the trajectory of AI use and valuation continues its current exponential path, the societal ramifications will be profound. The traditional link between human labor and economic compensation faces an unprecedented stress test. Companies that successfully leverage frontier models will achieve hyper-efficient margins, while legacy institutions slow to adapt risk rapid obsolescence.
Whether Anthropic’s IPO and the broader market enthusiasm represent a speculative bubble or a remarkably accurate preview of history depends entirely on the next generation of model breakthroughs. What remains indisputable is that the boundary between human cognition and machine capability has irrevocably blurred, setting the stage for an economic and technological transformation unlike any in human history.